Home › Blog › Loans by amount and term › ₱3,000 Loan Online Philippines: Terms & Real Cost
₱3,000 Loan Online Philippines: Terms & Real Cost
₱3,000 can cost you ₱3,732 or ₱5,160 depending on the term you pick. See where to borrow 3000 pesos and which plan fits your paydays.
Published November 1, 2026
The rice, the electric bill and the LPG refill all landed in the same week. Or your phone screen cracked and you need it for work. Or a cousin's wedding is on Saturday and the ninong gift cannot wait. ₱3,000 is the amount that keeps a normal month from falling apart.
At ₱3,000, many borrowers want to spread repayment over a few paydays, and that is where costs grow quietly. One lender's own example shows ₱3,000 turning into ₱5,160 over six months. This page shows where to get a 3000 pesos loan online, how the term changes your bill, and which choice fits your paydays.
Try other terms in the calculator below. It is set to ₱3,000 for 90 days and uses a general illustrative rate, not a Honey Loan quote. The real figure is in your lender's disclosure statement, and the tables below use the rates the lenders publish.
Estimate your Honeyloan repayment
Illustrative only — the lender sets the final rate. Honeyloan sets your actual rate, fees and schedule and shows them on its own site before you sign. This is an illustration, not an offer.
Where to borrow ₱3,000 online
Each option below includes ₱3,000 in its published range. The lenders are on the SEC list dated 20 October 2026; the matching services are free.
- 0.4% a day, maximum APR 144%
- Pay in installments or all at once
- Payout to GCash, Maya or a bank
- Age 21 to 70, terms 61 to 364 days
- Terms of 6 to 48 months
- 2.49% to 8.49% a month, per its app listing
- Offered mainly to existing customers; 3% processing fee, max ₱1,000
- 0.2% interest plus 0.2% service fee a day
- 1 valid ID, no collateral or references
- Terms of 61 to 180 days
- 1 valid ID and a mobile number
- Up to 120 days, repay any time
- Processing fee 3.99%–9.99% plus 0.23%–0.43% a day
- Partner terms of 3 to 12 months, says its site
- Some lenders "may" offer a first loan at 0%
- Not a lender: check who approves you
- No service fee for you, says Crezu
- Terms of 91 to 120 days
- Not a lender: check who approves you
How much does a ₱3,000 loan really cost?
Honey Loan publishes a representative example for exactly this amount: ₱3,000 for 180 days, ₱2,160 in total interest and fees, ₱5,160 to repay, or ₱860 a month. That works out to 0.4% a day, or 12% a month. The monthly payment looks gentle, but you repay 72% more than you borrowed.
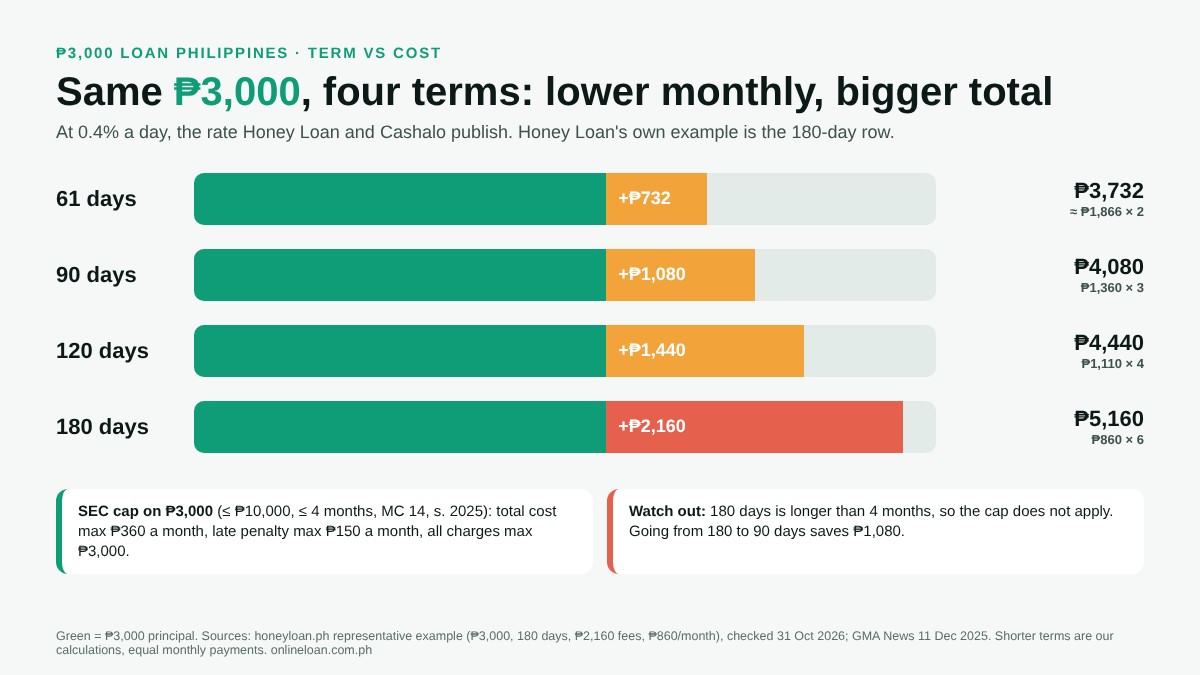
The same 0.4% a day over shorter terms, by our calculation:
| Term | Fees on ₱3,000 | Total (per month) |
|---|---|---|
| 61 days | ₱732 | ₱3,732 (about ₱1,866 × 2) |
| 90 days | ₱1,080 | ₱4,080 (₱1,360 × 3) |
| 120 days | ₱1,440 | ₱4,440 (₱1,110 × 4) |
| 180 days | ₱2,160 | ₱5,160 (₱860 × 6) |
We assume equal monthly payments and a flat 0.4% a day on the full ₱3,000, as in Honey Loan's example. Cashalo charges the same 0.4% a day, split into 0.2% interest and 0.2% service fee, so the table fits it too.
How the other benchmarks compare
Tala charges a one-time processing fee plus a daily fee. Using its listed ranges (Google Play, updated 29 October 2026), ₱3,000 for 61 days costs between ₱540.60 (3.99% + 0.23% a day) and ₱1,086.60 (9.99% + 0.43% a day), by our math. The top of that range is above the ₱732 the SEC cap allows for 61 days on ₱3,000, so on a covered loan your offer should come in lower. Repay early and the daily part shrinks.
Home Credit works differently. Its cash loans start at ₱3,000, but terms run 6 to 48 months at 2.49% to 8.49% a month, with a 3% processing fee (maximum ₱1,000) taken from the proceeds. On ₱3,000, that fee is ₱90, so ₱2,910 reaches you. Cash loans go to qualified existing customers, so a first-timer may not see the offer.
Key point. On ₱3,000, the cheapest plan is the one with the fewest days you can honestly afford. Moving from 180 to 90 days at the same rate saves ₱1,080, even though the monthly payment rises from ₱860 to ₱1,360.
Ready to borrow ₱3,000? Compare partner offers that include ₱3,000 and check the total repayment in pesos before you sign.
Compare offersThe legal limit on a ₱3,000 loan
SEC Memorandum Circular No. 14, series of 2025, covers loans of ₱10,000 or less with terms of up to four months and no collateral, entered into from 1 April 2026. On a covered ₱3,000 loan:
- Interest: at most 6% a month, so ₱180 a month.
- Total cost (interest plus fees): at most 12% a month, so ₱360 a month.
- Late penalty: at most 5% a month on the overdue amount, so ₱150 a month if all ₱3,000 is overdue.
- Everything together: never more than 100% of the principal, so charges stop at ₱3,000 and the most you could owe is ₱6,000.
The catch: a 180-day loan, or any Home Credit cash loan (six months or more), is longer than four months, so these caps do not apply. Honey Loan's 180-day example still sits at 12% a month, but on long terms the cap does not protect you. Read our 2026 rate cap explainer and learn to check a lender on the SEC list.
How to get ₱3,000 online in 4 steps
- Match the term to your paydays. Count how many paydays you need to repay ₱3,000 plus fees. Two payday cycles is cheaper than six.
- Choose an SEC-recorded app. See our legit loan apps guide. For matching services, check the lender's name before you accept.
- Prepare one valid ID. Honey Loan, Cashalo and Tala say one ID is enough. Home Credit also asks for a source of income. Our documents guide lists accepted IDs.
- Read the disclosure, then pick your payout. Confirm the total in pesos and the payment dates. Honey Loan lists GCash, Maya and bank transfer.
Who can borrow ₱3,000?
Honey Loan accepts Filipino citizens aged 21 to 70 with a valid government ID and an active mobile number. Tala accepts Philippine resident citizens 18 and up with one valid ID and a mobile number. Home Credit's own page says Filipino citizens aged 18 to 68 with a valid ID and a source of income, with cash loans offered to qualified existing customers. Finami says applicants must be 18 or older. See our approval tips.
Real scenarios: which ₱3,000 plan fits?
Joanna, 31, paid every 15th and 30th. She needs ₱3,000 for bills and can spare about ₱1,400 a month. A 90-day plan at 0.4% a day (₱1,360 a month, ₱4,080 total) fits her budget and costs ₱1,080 less than 180 days.
Ramil, 38, contract construction worker. His income is irregular, so he eyes ₱860 a month over six months, which costs ₱2,160 in fees. If his next contract starts soon, 120 days (₱1,110 a month) saves ₱720.
Bea, 24, delivery rider. Her phone repair costs ₱3,000, and without the phone she earns nothing. She borrows where early repayment cuts the fee and repays in two paydays.
Tonyo, 27, wants a ₱3,000 gaming headset. Over 180 days it would cost him ₱5,160. Saving ₱500 a payday gets him there in three months, fee-free.
Cheaper ways to find ₱3,000
Check first if your employer offers a salary advance. If you are an SSS member, check whether you qualify for its salary loan. A 0% first-loan promo can make a short loan free; see our zero-interest first loan guide. For in-wallet credit, read our GCash GLoan, GGives and GCredit guide.
Checklist before you borrow ₱3,000
- The lender's company name is on the SEC List of Recorded Online Lending Platforms.
- You know the total repayment, not just the monthly payment.
- On a term of four months or less, total cost is no more than ₱360 a month.
- Any processing fee taken from the payout is shown upfront.
- Each due date falls on or after a payday.
- You checked whether paying early lowers the fee.
- You never pay anything before the money arrives.
Quick answers
Where can I borrow ₱3,000 online in the Philippines? Honey Loan (₱1,000 to ₱10,000 for new clients), Tala (₱1,000 to ₱25,000) and Cashalo (up to ₱13,000) all include ₱3,000. Home Credit cash loans start at ₱3,000 for qualified existing customers. Finami and Crezu forward requests to partner lenders.
How much will I repay on a ₱3,000 loan? At 0.4% a day: ₱3,732 after 61 days, ₱4,080 after 90 days, ₱4,440 after 120 days, and ₱5,160 after 180 days, which is Honey Loan's own example.
Can I get ₱3,000 the same day? Often. Honey Loan says validation usually takes 2 to 3 minutes and money is credited instantly to GCash, Maya or a bank after approval. Approval is never guaranteed.
Can I borrow ₱3,000 without a payslip? Yes, at several apps. Honey Loan says you only need your ID, and Tala and Cashalo ask for one valid ID. Our no-payslip loan guide has more options.
Is Honey Loan legit? Yes. Honey Loan is listed under Warm Cash Lending Corp., SEC No. 2021030009095, on the SEC list dated 20 October 2026.
What if I cannot repay ₱3,000 on time? On a covered loan, the late penalty is capped at ₱150 a month on a fully overdue ₱3,000, and total charges cannot pass ₱3,000. Talk to the lender before the due date and read what happens if you miss a payment.
Other loan amounts
Looking at more apps and higher limits? Read our guide to the best online loan apps in the Philippines or go straight to compare offers.
Sources: honeyloan.ph representative example and terms (checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; Cashalo Google Play listing (updated 12 Oct 2026); Tala Google Play listing (updated 29 Oct 2026); My Home Credit Google Play listing (updated 25 Sep 2026) and homecredit.ph "How much can you borrow" (updated 28 May 2026), checked 31 Oct 2026; finami.ph and crezu.ph (checked 31 Oct 2026); GMA News, 11 Dec 2025, and cashalo.com notice on SEC MC No. 14, s. 2025 (effective 1 April 2026). Term tables and Tala ranges are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Honeyloan?
Honeyloan
Compare available lending offers
Review the final repayment amount and terms on the provider's website