Home › Blog › Best loan apps by need › Loan Without Payslip Philippines: 7 Options 2026
Loan Without Payslip Philippines: 7 Options 2026
No payslip does not mean no loan. Here is what freelancers, online sellers and gig workers can show instead, and what each route costs in pesos.
Published November 1, 2026
It is the 28th, and your Upwork client has paid. The money sits in your GCash, ₱38,000 from three projects this month. Then your laptop dies, and a repair shop quotes ₱9,500. You open a lending app, tap "Apply", and the form asks for your company name, your HR phone number and your last three payslips. You have none of that. You have invoices, a GCash history and a BIR receipt from last quarter.
That is everyday life for Filipinos who earn outside a payroll: freelancers, online sellers, riders, store owners, tutors and VAs. A payslip is not the only key. Several SEC-recorded apps say you need one valid ID, SSS lets self-employed and voluntary members borrow against their contributions, and at least two big banks list exactly which documents a self-employed borrower can submit instead.
We checked each option against the provider's own website, Google Play listing or government page on 31 October 2026. Below you will find who accepts what, what it costs in pesos, and which route fits your kind of income. This site is a comparison service, not a lender, and some partners pay us a referral fee when you apply.
7 ways to get a loan without a payslip
The first four are app loans that ask for an ID rather than proof of employment. The next two are slower but much cheaper routes built for people who can show contributions or business papers. The last one is a matching service. "Lender" means the company that signs the loan with you. "Matching service" means a free site that passes your application to lenders.
- Its site says "No payslip document required"
- Employed or with a regular source of income, age 20–70
- Decision in 10 minutes to 1 working day
- Paid out to GCash, Maya or a bank account
- Rate and fees shown only during the application
- Requirements listed: valid government ID, active mobile number
- 0.4% a day, maximum APR 144%, published
- New clients up to ₱10,000, repeat up to ₱30,000
- Age 21–70; a credit check still applies
- 1 valid ID and a mobile number, 18+
- No bank account needed, per its listing
- Up to 120 days, repay any time
- Fees are personalised: 3.99–9.99% + 0.23–0.43% a day
- "1 Valid ID, no collateral or references needed"
- 61–180 days, 0.4% a day all-in
- Paid out to GCash, Maya, GoTyme, BPI, BDO
- Reads SMS and app data to assess you
- 1% service fee, 24 monthly payments
- Your posted contributions replace the payslip
- Apply online in My.SSS or the MySSS app
- Needs 36 posted contributions, 6 under your current type
- Self-employed: DTI or SEC registration plus one income document
- ITR/BIR 1701, audited FS or 2 months of bank statements
- 12–36 months, annual contractual rate up to 31.72%
- 5–7 working days, ₱1,500 processing fee
- Asks for a valid PH ID and a bank account
- No payslip mentioned; free, no service fee
- Not a lender: check who approves you
Tala and Cashalo are not partners; we include them because their Google Play listings say clearly that an ID is enough. All four apps above are on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026. For the full registered list, see our legit loan apps hub.
How we chose these options
An option made this list only if it passed four tests, not by commission.
- The provider says it in writing. The no-payslip claim, or the list of accepted self-employed documents, had to appear on the provider's own site, help page or app listing.
- It is regulated. App lenders had to be on the SEC list of 20 October 2026. SSS is a government agency, and BPI is a bank.
- The paperwork is realistic for non-employees. One ID, contribution records, business registration or bank statements all count. A certificate of employment does not.
- You can see the price, or at least where it appears. Published rates got credit. Where a lender shows its rate only inside the application, we say so.
What lenders accept instead of a payslip
A payslip does one job: it proves that money comes in every month. If you work for yourself, you prove the same thing with other papers. Here is what each type of provider says it accepts, as of 31 October 2026.
| Your proof | Who accepts it | Speed |
|---|---|---|
| 1 valid ID + selfie | Finbro | Minutes to 1 day |
| 1 valid ID + mobile number | Honey Loan, Tala, Cashalo | Minutes |
| SSS contributions | SSS salary loan | Days |
| DTI/SEC + ITR or 1701 | BPI, CIMB | About a week |
| Bank statements | BPI (2 months), CIMB (6 months) | About a week |
None of this guarantees approval. ID-only apps still check you; Cashalo's listing, for example, says it uses location, installed-app and SMS data. One ID gets you through the door, not a yes.
Finbro's FAQ accepts SSS, UMID, driver's license, passport, national ID and postal ID. Our documents guide covers the rest.
The options in detail
Finbro: one ID, a selfie and a regular income
Finbro is run by Sofi Financing Inc. (SEC No. CS201908275, Certificate of Authority No. 1324). Its homepage says it only takes "one valid ID and selfie", and adds "No payslip document required". The FAQ asks for a Filipino citizen aged 20 to 70 who is "employed or with regular source of income". That second phrase matters for freelancers: you do not have to be an employee, but you do need money coming in.
Processing takes from 10 minutes to one working day during working hours, and disbursements to GCash, Maya or a bank account are real-time after approval. If a client pays you late, Finbro has a minimum payment option that moves your next payment date by 7, 14 or 30 days. You can also repay in full before the due date with no extra cost.
The one weakness: Finbro does not publish its interest rate or processing fee. Its FAQ says you see both during the application, before you confirm the loan agreement. Read the disclosure statement before you tap "Confirm". Full details are in our Finbro loan review.
Honey Loan: ID-only requirements and a published price
Honey Loan is run by Warm Cash Lending Corp. (SEC No. 2021030009095, Certificate of Authority No. 3472). Its homepage lists four requirements: Filipino citizen aged 21 to 70, a valid government ID, an active mobile number that is not blocked, and registration on its website. Proof of income is not on the list, though the site does mention a credit check.
What makes it useful for sellers is that the price is printed upfront: 0.4% a day and a maximum APR of 144%. Its own example is ₱3,000 for 180 days, which costs ₱2,160 in interest and fees, so you repay ₱5,160 in monthly installments of ₱860. New clients can borrow up to ₱10,000; repeat clients up to ₱30,000.
Tala and Cashalo: two well-known ID-only apps
Tala's Google Play listing (updated 29 October 2026) says "No income proof needed" and "Only 1 valid ID is needed", with no paperwork, collateral or bank account. Credit limits run from ₱1,000 to ₱25,000 for up to 120 days. Fees are personalised, from a 3.99% to 9.99% processing fee plus 0.23% to 0.43% a day. Tala is not a partner of this site; see our Tala review.
Cashalo's listing (updated 12 October 2026) says you need "1 Valid ID" and no collateral or references. It lends up to ₱13,000 for 61 to 180 days at 0.4% a day in interest plus service fee. It is operated by Paloo Financing, Inc. (SEC No. CS201800209).
SSS Salary Loan: the cheapest route for self-employed members
If you have been paying SSS as a self-employed or voluntary member, your contribution record does the job of a payslip. According to the SSS salary loan page (checked 31 October 2026), self-employed members, voluntary members and non-working spouses can borrow if they have:
- 36 posted monthly contributions, 6 of them within the last 12 months, for a one-month loan;
- 72 posted monthly contributions for a two-month loan;
- and, on top of that, at least 6 posted monthly contributions under their current membership type.
You must also be under 65, have no past-due salary loan, and have a disbursement account enrolled in DAEM in your My.SSS account. A one-month loan equals the average of your 12 latest posted monthly salary credits (MSC); a two-month loan is twice that.
The price is the best you will find anywhere: 8% a year on the diminishing balance for first loans and renewals without a penalty condonation in the past five years, plus a 1% service fee deducted from the proceeds. You repay in 24 equal monthly amortizations. Late payment costs 1% a month, so do not let it slide.
The catch is the word "posted". If you paid contributions only in bursts, or you recently switched from employee to self-employed, count your last 12 months and your current-type months before applying. You apply online in My.SSS or the MySSS app, and money goes to your MySSS Card, UMID ATM card or a PESONet bank account in your name.
Banks: BPI and CIMB list self-employed documents
Banks are slower, but they say plainly what a self-employed borrower can submit. BPI's personal loan FAQ (checked 31 October 2026) asks all applicants for one valid government ID, a signed application form and income documents. For the self-employed, that means a DTI or SEC business registration certificate plus any one of: the latest audited financial statements, an ITR or BIR Form 1701, or bank statements for the last two consecutive months.
BPI lends ₱20,000 to ₱3,000,000, up to three times your gross monthly income, over 12 to 36 months. The annual contractual rate is up to 31.72%, there is a one-time ₱1,500 processing fee, and processing takes 5 to 7 working days after complete documents.
CIMB's help page lists a stricter set for self-employed and freelancers: DTI or SEC registration, a mayor's permit, and either BIR Form 1701 or the latest six months of bank statements.
No payslip, need cash this week? Start with an app that asks for one ID, then compare the total repayment before you sign.
Compare offersWhat a no-payslip loan costs in pesos
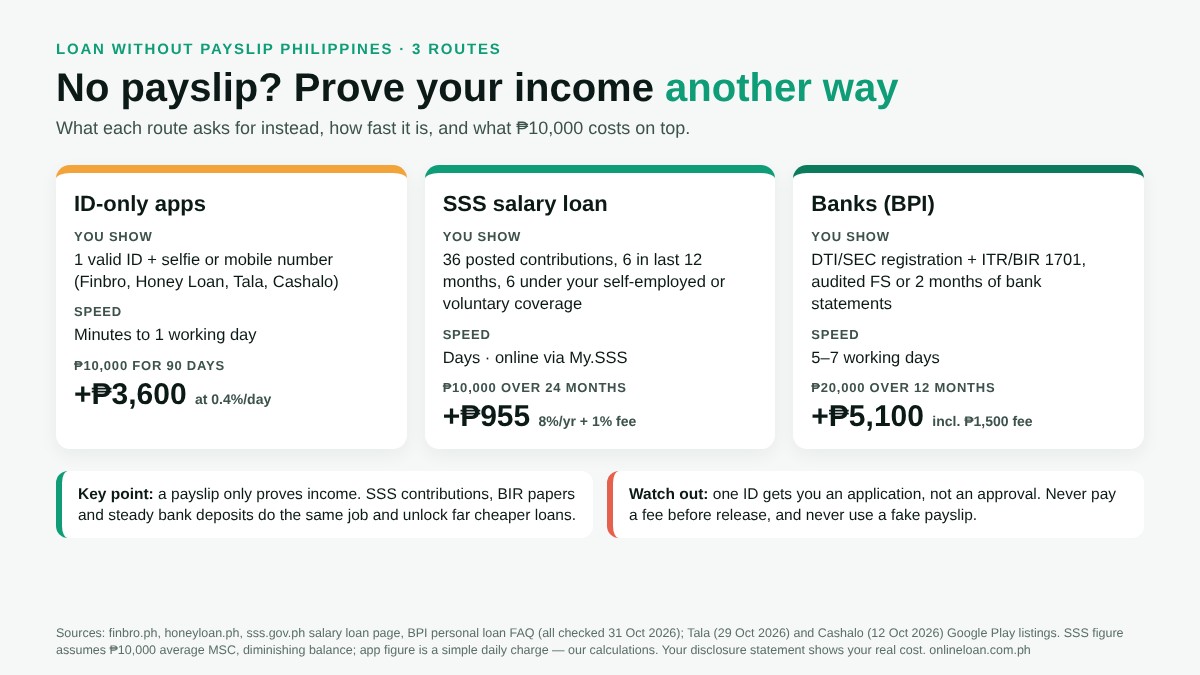
Skipping the payslip does not have to mean paying more. It depends on which door you use. The infographic below puts the three routes side by side.
| Route and loan | Cost on top | How you repay |
|---|---|---|
| App at 0.4%/day · ₱10,000 · 90 days | ₱3,600 | One or more payments |
| SSS · ₱10,000 one-month loan | ₱955 | ₱452.27 × 24 months |
| SSS · ₱20,000 two-month loan | ₱1,909 | ₱904.55 × 24 months |
| BPI · ₱20,000 · 12 months | ₱5,100 | ₱1,966.67 × 12 months |
How we worked these out. App row: ₱10,000 × 0.4% × 90 days, the published rate of Honey Loan and Cashalo, simple daily charge, no late fees. SSS rows: 8% a year on the diminishing balance over 24 equal monthly payments, our calculation, plus the 1% service fee (₱100 or ₱200); the SSS loan rows assume an average MSC of ₱10,000. BPI row: BPI's own example of ₱20,000 for 12 months, total repayment ₱23,600, plus the ₱1,500 processing fee deducted from proceeds. Your real cost is the one in your disclosure statement.
For about the same ₱10,000, a three-month app loan costs almost four times what SSS charges over two years. The app wins on speed; SSS wins on price. Our separate guide to the lowest-interest loan apps ranks every published price we could verify.
Key point. A payslip is just proof of income. If you have SSS contributions, BIR papers or steady bank deposits, you can unlock loans far cheaper than an ID-only app. Use the app for speed, and the cheaper route for anything that can wait a week.
Also remember the SEC's small-loan rule under Memorandum Circular No. 14, series of 2025, in effect since 1 April 2026: for loans of ₱10,000 or less with terms up to four months, the total cost may not exceed 12% a month, and all charges together may not exceed 100% of what you borrowed. On a ₱10,000 app loan that means no more than ₱10,000 in charges, ever. Our 2026 rate cap explainer has the details.
Build your "payslip substitute" folder
Lenders that assess non-employees look for money arriving regularly. Put these in one folder on your phone before you apply; not every lender asks for each item.
- One valid ID, ideally PhilSys, UMID or a driver's license, plus a clear selfie in good light.
- E-wallet and bank history for the last two to six months, showing client payments, platform payouts or sales deposits.
- BIR registration and returns, such as your Certificate of Registration and latest ITR or BIR Form 1701, if you are registered.
- DTI or SEC registration and, for some banks, a mayor's permit.
- Your SSS contribution record from My.SSS, showing posted months and your current membership type.
- Contracts or invoices from your biggest clients, in case a lender asks you to explain a deposit.
Not BIR-registered yet? Items 1 and 2 still help with apps, and registering later opens bank loans. Our guide on improving approval chances explains what else helps.
Real scenarios: which route fits your income
Rhea, 29, Shopee and TikTok Shop seller, needs ₱8,000 for 11.11 stock. Her sales land in GCash, but she has no payslip and no BIR papers. She needs the money in two days. An ID-only app is her realistic option. She compares Finbro's offer with Honey Loan's published 0.4% a day: on ₱8,000 for 61 days that is ₱1,952 in charges, our calculation. She picks the shortest term she can cover from the sale and repays early if sales go well.
Paolo, 35, freelance web developer, wants ₱20,000 for a new laptop. He has paid SSS as a self-employed member for eight years. With more than 72 posted contributions and an average MSC of ₱10,000, a two-month SSS loan could give him ₱20,000. Our estimate: ₱904.55 a month for 24 months, plus a ₱200 fee. He can wait a few days, so SSS beats any app by thousands of pesos.
Jomar, 26, delivery rider, a ₱3,000 gap before his weekly payout. His income is real but irregular, and he started SSS as self-employed only four months ago, so he does not yet have 6 posted months under his current type. A small app loan works if he repays on payout day. At 0.4% a day, ₱3,000 for 61 days costs ₱732; repaying sooner should cost less, so he checks how early repayment works in the disclosure statement.
Lea, 31, VA between clients, thinking of borrowing ₱15,000 to cover two months of rent. We would say wait: with no confirmed income next month, any loan risks late fees. She talks to her landlord and borrows only once a new contract is signed. If you are already behind, read what happens when you miss a payment.
How these compare with other popular apps
Other apps you will see in the Play Store, all on the SEC list of 20 October 2026:
Red flags when you have no payslip
People without payslips are a favourite target of fake lenders, because "no requirements" sounds like a lifeline. Walk away if an app or Facebook page asks for a "processing" or "insurance" fee before releasing the loan, promises guaranteed approval, has no SEC registration number and Certificate of Authority on its site, or wants your contacts and photo gallery.
Never pay an "agent" to fake a payslip for you: false documents are a far bigger problem than unpaid debt, which on its own is not a crime (see this guide). More warning signs: loan scam red flags.
Checklist before you apply without a payslip
- Decide whether you need the money this week or can wait a few days. If you can wait, check SSS or a bank first.
- Log in to My.SSS and count your posted contributions: total, last 12 months and months under your current type.
- For an app, look up the lender's company name on the SEC's List of Recorded Online Lending Platforms.
- Gather your ID, a selfie and two to six months of e-wallet or bank history before you start.
- Find the total repayment in pesos in the disclosure statement, not just the daily rate.
- Pick a due date that falls after your most reliable client payment or payout, not your hoped-for one.
- Check what a minimum payment or extension costs, in case a client pays late.
- Never pay a fee before the loan is released.
Quick answers
Can I get a loan without a payslip in the Philippines? Yes. Finbro says "No payslip document required", Tala says "No income proof needed", and Honey Loan and Cashalo list only an ID and mobile number. SSS and banks such as BPI accept contributions or business documents instead.
Which loan app needs only 1 valid ID? Tala and Cashalo both say "1 valid ID" in their Google Play listings. Finbro asks for one valid ID and a selfie. Honey Loan lists a valid government ID and an active mobile number.
Can freelancers and self-employed people get an SSS loan? Yes, if they have 36 posted monthly contributions, 6 within the last 12 months, plus at least 6 under their current self-employed or voluntary coverage. The rate is 8% a year with a 1% service fee, over 24 months.
What can I submit to a bank instead of a payslip? BPI accepts DTI or SEC registration plus one of: audited financial statements, an ITR or BIR Form 1701, or two months of bank statements. CIMB asks for DTI or SEC registration, a mayor's permit and BIR 1701 or six months of bank statements.
Is Finbro legit? Yes. Sofi Financing Inc., operating as Finbro.ph, is on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026, SEC No. CS201908275.
Is a no-payslip loan more expensive? Not necessarily. ID-only apps that publish their price charge 0.4% a day, about 12% a month. SSS charges 8% a year. The price depends on the route, not on the payslip.
Ready when you are: compare offers, or go straight to Finbro if you want an ID-and-selfie application from an SEC-recorded lender. For a ranking of options by your situation, see our best online loan apps.
Sources: finbro.ph homepage and FAQ (checked 31 Oct 2026); honeyloan.ph homepage (checked 31 Oct 2026); Tala Google Play listing (updated 29 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026); crezu.ph homepage (checked 31 Oct 2026); SSS Salary Loan page, sss.gov.ph (checked 31 Oct 2026); BPI Personal Loan new applicants FAQ, bpi.com.ph (checked 31 Oct 2026); CIMB Bank PH help page on acceptable income documents (checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC Memorandum Circular No. 14, series of 2025, as reported by GMA News (11 Dec 2025). Peso examples other than the providers' own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website