Home › Blog › Loans by amount and term › 7-Day Loan Philippines: Borrow for a Week Safely
7-Day Loan Philippines: Borrow for a Week Safely
Need cash for one week? Borrow from a registered lender and repay on day 7. Here is what it costs, and the 7-day trap to avoid.
Published November 2, 2026
It is Tuesday. Your salary lands next Tuesday, and today the water bill, a ₱1,800 school project and your phone load all fell due together. You do not need a six-month loan. You need ₱3,000 for one week, and you want to pay it back the moment the money arrives.
So you search "7 days loan", and the results split in two. On one side: well-known apps whose terms start at 61 days. On the other: unknown apps and Facebook pages promising "7 days, approved in 5 minutes". The second group is exactly where many Filipinos have ended up with half the loan deducted upfront and collectors calling their contacts on day 8.
This page explains why legitimate apps do not sell 7-day loans, how to borrow for a week anyway by repaying a longer loan early, and what that costs in pesos. We checked the sources on 1 November 2026. This site is a comparison service, not a lender, and some partners pay us a referral fee when you apply.
The calculator below starts at its shortest setting, 30 days, because it is built for standard terms. Treat it as an illustration with a general rate, not a quote from Finbro. For a 7-day repayment, use the peso tables further down.
Estimate your Finbro repayment
Illustrative only — the lender sets the final rate. Finbro sets your actual rate, fees and schedule and shows them on its own site before you sign. This is an illustration, not an offer.
Why legit loan apps don't offer 7-day loans
Google Play's Financial Services policy, checked on 1 November 2026, does not allow apps for personal loans that must be repaid in full within 60 days. It also requires Philippine lending apps to show their SEC registration number and Certificate of Authority. That is why the big names start at 61 days: Honey Loan and Cashalo list 61 days as their shortest term, and Tala's own cost example uses 61 days.
So an app that advertises a loan you must repay in full in 7 days is, by Google's own rule, not one Google allows. Many of these apps are sideloaded APKs or links shared on Facebook, Telegram or SMS. Some are not on the SEC list at all.
Key point. You can still borrow for a week. Take a loan with a normal term from a registered lender and repay it early. What you must avoid is a loan whose contract forces full repayment in 7 days, especially with fees taken upfront.
Philippine law does not set a minimum loan term, so a short contract is not automatically illegal. But the cost rules still apply. For unsecured loans of ₱10,000 or less with terms of up to four months, SEC Memorandum Circular No. 14, series of 2025, in force since 1 April 2026, caps interest plus fees at 12% a month and all charges at 100% of the principal. Our rate cap explainer has the details.
Where to borrow for one week
These options let you repay early. The cards show what each lender publishes about early repayment.
- Full repayment on or before the due date "without additional costs", its FAQ says
- Payout to GCash, Maya or a bank, decision in 10 minutes to 1 working day
- Minimum payment moves the due date by 7, 14 or 30 days
- Rate and fees shown only during the application
- 0.4% a day, maximum APR 144%
- "Repay it early at your own convenience", its FAQ says
- Age 21–70; term of up to 12 months on the contract
- Daily service fee of 0.23–0.43% for each day the loan is open
- 1 valid ID, 18+
- Plus a one-time processing fee of 3.99–9.99%
All three are on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026. Before you rely on early repayment, read the disclosure statement: it tells you whether interest is charged only for the days you actually use the money, and whether any fee is deducted upfront.
How much does a 7-day loan cost?
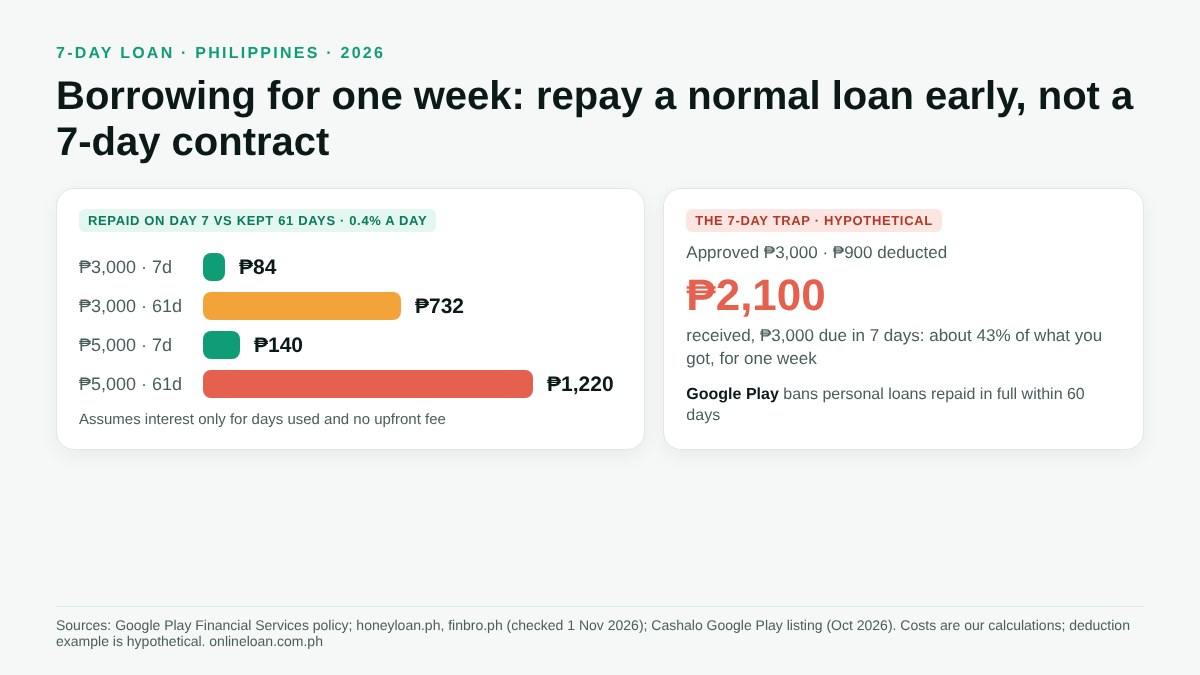
At a published price of 0.4% a day, charged only for the days used, a week is cheap. The same loan kept for the full 61-day term costs almost nine times as much.
| Loan | Repaid on day 7 | Kept 61 days |
|---|---|---|
| ₱1,000 | ₱28 | ₱244 |
| ₱3,000 | ₱84 | ₱732 |
| ₱5,000 | ₱140 | ₱1,220 |
| ₱10,000 | ₱280 | ₱2,440 |
How we calculated. Loan × 0.4% × days, the published daily price of Honey Loan and Cashalo, assuming interest accrues only for the days the loan is open and no fee is deducted upfront. Check both points in your disclosure statement.
When a one-time fee changes the math
Some lenders charge a processing fee once, at the start. Then early repayment usually saves the daily charges but not that fee. On Tala's published ranges, a ₱1,000 loan repaid after 7 days costs a ₱39.90–₱99.90 processing fee plus ₱16.10–₱30.10 in daily fees: ₱56 to ₱130 in total, our calculation. That is still far less than keeping it 61 days, but the first week is the most expensive week.
Need cash until payday? Borrow from an SEC-recorded lender that lets you repay early at no extra cost, then repay on day 7.
Check your Finbro offerThe 7-day trap: how a "₱3,000 loan" becomes ₱2,100
The pattern behind most complaints about short-term apps looks like this. The app approves "₱3,000", deducts a "service fee" before sending the money, and wants the full ₱3,000 back in 7 days. Here is a hypothetical example, to show the math:
| Amount | |
|---|---|
| Approved | ₱3,000 |
| Deducted upfront | ₱900 |
| You receive | ₱2,100 |
| You repay on day 7 | ₱3,000 |
| Real cost for one week | ₱900, about 43% of what you got |
At that pace, borrowers often take a second app loan to pay the first, then a third. The SEC counts every fee as a charge: on a covered ₱3,000 loan, interest plus fees may not exceed ₱360 a month. If you are already caught in this, read our guides on what happens if you miss a payment and how to report online loan harassment. Unpaid debt on its own is not a crime: see can you go to jail for an unpaid online loan.
How to borrow for exactly one week, step by step
- Pick a registered lender. Check the company name on the SEC list; our legit loan apps hub shows how.
- Read the early-repayment rule. In the disclosure statement, find whether interest is charged for days used and whether anything is deducted upfront.
- Borrow only what one paycheck clears. If your salary is ₱12,000, a ₱3,000 loan you repay in full on payday is realistic. ₱9,000 is not.
- Repay on day 7 through an instant channel. E-wallets and payment centers usually post fast; bank transfers can take days. Keep the receipt.
Real scenarios
Jessa, 27, BPO agent, needs ₱3,000 until next Tuesday's payday. She borrows from a registered lender with a 61-day contract and pays it all back on payday. At 0.4% a day, 7 days cost her ₱84 instead of ₱732.
Mark, 34, rider, gets a Facebook message: "₱5,000 in 7 days, no requirements". The link leads to an APK, not Google Play, and the company is not on the SEC list. He closes it. A loan like that can cost him his contacts' privacy as well as his money.
Lorna, 45, store owner, borrowed from a 7-day app and got ₱2,100 of a ₱3,000 loan. She stops borrowing from new apps to pay old ones, writes down every charge, contacts the lender in writing and checks whether it is on the SEC list. If it is not, she reports it.
When not to borrow. If you are not sure the money arrives within a week, a "7-day" plan can turn into a 61-day loan with penalties. Ask your employer for a salary advance first.
Cheaper ways to cover one week
Ask your employer about a salary advance or a cash advance on your next payroll. If you have SSS contributions, the SSS salary loan is far cheaper, though not same-day. A pawnshop loan against gold or a gadget is another short-term option; compare it in loan apps vs banks vs pawnshops. For wallet-based credit, see our GCash loans guide.
Checklist before a one-week loan
- The app is on Google Play or the App Store, not an APK from a link.
- The lender's company name is on the SEC list of recorded online lending platforms.
- The disclosure statement shows no large fee deducted upfront.
- You know whether early repayment cuts the interest.
- The amount fits inside one paycheck.
- You set a reminder for the day your money arrives.
- You never pay a "release fee" before getting the loan.
Quick answers
Is there a 7-day loan app in the Philippines? Not among apps Google Play allows: its policy bans personal loans that must be repaid in full within 60 days. You can borrow from a registered lender and repay in 7 days instead.
How much is a 7-day loan of ₱5,000? At 0.4% a day for days used, ₱140, so ₱5,140 in total. A lender that deducts a one-time fee upfront will cost more.
Can I repay a Finbro loan in 7 days? Yes. Finbro's FAQ says you can repay the whole loan on or before the due date without additional costs.
Are 7-day loan apps legal? A short term alone is not illegal, but the lender must be SEC-registered and stay within the cost caps. An app that deducts big fees upfront or is not on the SEC list is a red flag.
Can I get a loan same day and pay next week? Yes, if you are approved. Finbro says disbursement is real-time after approval and Honey Loan says checks usually take 2 to 3 minutes; approval is never guaranteed.
What if I can't repay after 7 days? With a normal-term loan, you are simply not late yet: you have until the due date. With Finbro, a minimum payment can also move the date by 7, 14 or 30 days.
Other loan amounts and terms
- 14-day loan until payday
- 30-day loan
- ₱1,000 loan online
- ₱3,000 loan online
- ₱5,000 loan online
- ₱10,000 loan online
- ₱15,000 loan online
Sources: Google Play Console Help, Financial Services policy (checked 1 Nov 2026); finbro.ph FAQ (checked 1 Nov 2026); honeyloan.ph homepage and FAQ (checked 1 Nov 2026); Tala Google Play listing (updated 29 Oct 2026) and Tala pricing FAQ; Cashalo Google Play listing (updated 12 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026 (checked 1 Nov 2026); SEC Memorandum Circular No. 14, series of 2025. The deduction example is hypothetical; other cost examples are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website