Home › Blog › Loans by amount and term › ₱5,000 Loan Online Philippines: Where to Borrow 5k
₱5,000 Loan Online Philippines: Where to Borrow 5k
₱5,000 short before payday? Here is where to borrow 5k online today, what it costs per day, and when an SSS salary loan is the cheaper move.
Published November 1, 2026
It is Thursday night and the electric bill on the fridge has a disconnection notice clipped to it. Add the tuition balance due before exams, and you are ₱5,000 short with eight days to payday. You need exactly ₱5,000, in GCash, by tomorrow morning.
₱5,000 is big enough to fix a real problem, small enough that most SEC-recorded apps cover it on a first loan, and fully inside the 2026 interest cap if the term is four months or less. Below: which apps lend ₱5,000, the cost per day and per month, and when an SSS salary loan beats an app.
Try a different term in the calculator below. It starts at ₱5,000 for 60 days and uses a general illustrative rate, not a Finbro quote. Finbro shows its real rate and fees only inside the application, so treat the result as a rough guide and check the cost tables further down.
Estimate your Finbro repayment
Illustrative only — the lender sets the final rate. Finbro sets your actual rate, fees and schedule and shows them on its own site before you sign. This is an illustration, not an offer.
Where to borrow ₱5,000 online
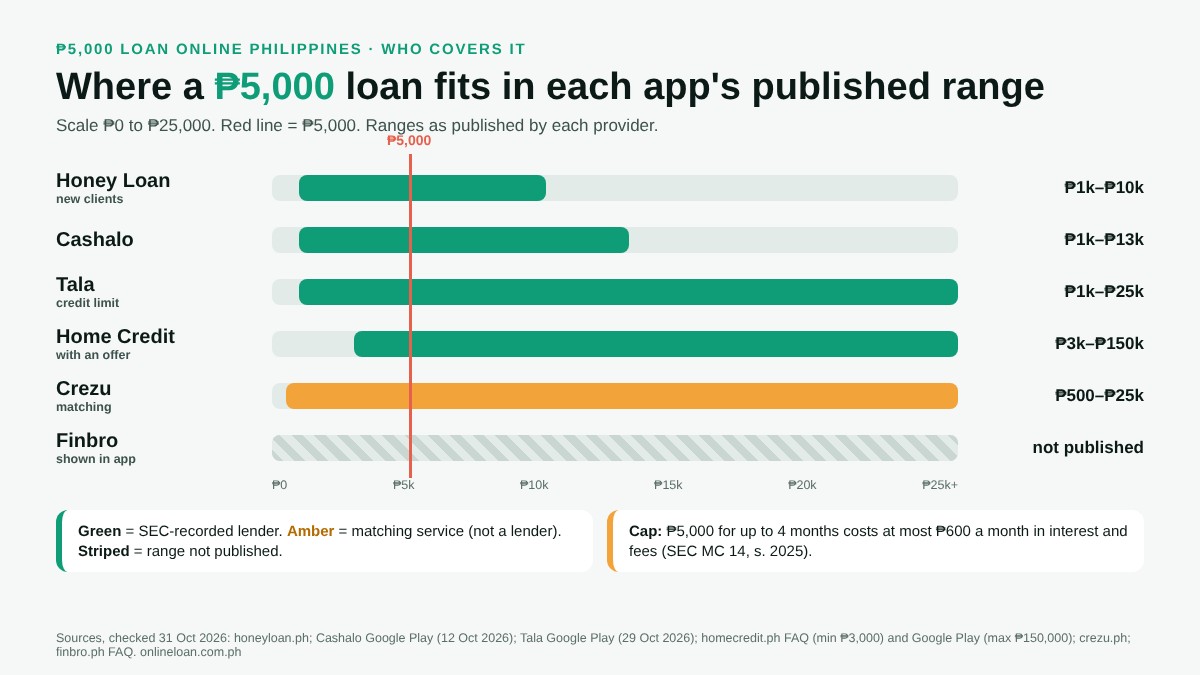
Each card below publishes a range that includes ₱5,000, except Finbro, which shows your offer during the application. Partners and benchmarks are marked.
- Sofi Financing Inc., SEC No. CS201908275
- Processing from 10 minutes to 1 working day; real-time disbursement after approval
- Minimum payment moves the due date by 7, 14 or 30 days
- Does not publish amount ranges or rates: you see your offer in the app
- Warm Cash Lending Corp., on the SEC list
- 0.4% a day, maximum APR 144%
- GCash, Maya or bank transfer, 24/7
- Age 21 to 70, terms from 61 days
- 1 valid ID, no income proof or bank account
- Up to 120 days, repay any time
- Processing fee 3.99%–9.99%, so ₱199.50–₱499.50 on ₱5,000
- Paloo Financing, Inc., on the SEC list
- 1 valid ID; bank, GCash or Maya payout
- Terms 61 to 180 days; proceeds in 1 to 3 days, it says
- Free for you, terms of 91 to 120 days
- Needs a valid PH ID and a bank account
- Not a lender: check who approves you
- HC Consumer Finance Philippines, on the SEC list
- Monthly installments, 2.49%–8.49% a month
- No offer, no loan: first-timers usually start with a store installment
How much does a ₱5,000 loan really cost?
We already show the full 0.4%-a-day table for ₱5,000 (61 to 180 days) in our best online loan apps guide. The short version: ₱6,220 after 61 days, ₱6,800 after 90. Here is what that guide does not cover.
| Option for ₱5,000 | What you pay | Total |
|---|---|---|
| Honey Loan / Cashalo, 61 days | ₱20 a day | ₱6,220 |
| Tala, 61 days (11–12% a month) | about ₱1,118–₱1,220 | ₱6,118–₱6,220 |
| Home Credit | 2.49%+ a month | per offer |
| SSS salary loan, 24 months | 8% a year + 1% fee | about ₱5,477 |
| Any covered loan, SEC cap | ₱600 a month max | ₱5,000 in charges max |
How we got these numbers. The 0.4% row is ₱5,000 × 0.4% × 61 days. Tala publishes a processing fee of 3.99%–9.99% and a service fee of 0.23%–0.43% a day; taken alone, those ranges would allow ₱901 to ₱1,811 over 61 days, but Tala also states a monthly effective rate of 11–12%, which on ₱5,000 for 61 days works out to roughly ₱1,118–₱1,220. The SSS row is our amortization of ₱5,000 at 8% a year on diminishing balance over 24 months (about ₱226 a month, ₱427 interest) plus the 1% service fee of ₱50; SSS also deducts prorated interest upfront, so your figure will differ slightly.
Every day is ₱20
At 0.4% a day, each day you keep ₱5,000 costs ₱20. Repay ten days earlier and you keep ₱200. Tala says you can repay any time and pay service fees only for the days used. Honey Loan and Cashalo terms start at 61 days, so pick the shortest term and ask about early payoff before you sign.
Key point. On ₱5,000 the gap between the cheapest and priciest sensible choice is about ₱1,000, the size of a week's groceries. Decide the repayment date first, then choose the app that charges only for those days.
Need ₱5,000 before payday? Compare partner offers and see the total repayment in pesos before you confirm.
Compare offersWhat the 2026 cap means for ₱5,000
Since 1 April 2026, SEC Memorandum Circular No. 14, series of 2025 limits charges on unsecured loans of ₱10,000 or less with terms of up to four months. A ₱5,000 loan for 120 days or less is covered. In pesos:
| Charge on ₱5,000 | Legal maximum |
|---|---|
| Interest | ₱300 a month |
| Interest plus all fees | ₱600 a month |
| Late penalty | ₱250 a month if all ₱5,000 is overdue |
| All charges together, ever | ₱5,000 |
Choose a 180-day term and the same ₱5,000 falls outside these caps. Honey Loan and Cashalo both state a maximum APR of 144% anyway, but the 100%-of-principal ceiling on penalties no longer comes from the rule. Our rate cap explainer has the details.
How to get ₱5,000 to GCash today
- Check the lender on the SEC list. Every lender on this page is recorded; see how to check in two minutes.
- Have one valid ID and your phone ready. UMID, driver's license, passport, PhilSys or postal ID. Finbro and many others ask for a selfie too. More in our documents guide.
- Enter ₱5,000, not the higher limit you are offered. Then read the disclosure statement: total repayment, due dates, deductions.
- Pick GCash or Maya as the payout. Finbro, Honey Loan and Cashalo all list e-wallets. For wallet-native credit, see our GCash loans guide.
Who can borrow ₱5,000?
Finbro accepts Filipino citizens aged 20 to 70 who are employed or have a regular income, and says no payslip document is required. Honey Loan wants citizens aged 21 to 70 with a government ID and an active mobile number. Tala accepts resident citizens 18 and up with one valid ID. First loan anywhere? Read our first-time borrower guide.
The slower, cheaper route: SSS salary loan
If you have been paying SSS for years, check this before any app. The SSS salary loan charges 8% a year on diminishing balance for first loans, plus a 1% service fee, repaid over 24 months. On ₱5,000 that is roughly ₱226 a month and about ₱477 in total cost, less than half of what 61 days at 0.4% a day costs.
The catch is eligibility and time. A one-month loan needs 36 posted monthly contributions, six of them in the last 12 months; self-employed, voluntary and land-based OFW members need at least six posted contributions under their current membership. You apply in My.SSS, an employed member's employer must certify the application, and the money goes to a disbursement account enrolled in DAEM. SSS does not promise same-day release.
Real scenarios: ₱5,000, yes or no?
Carlo, 34, delivery rider. His cracked phone means no bookings. A ₱5,000 repair pays for itself in days. He borrows, repays early from weekly earnings, and stops the ₱20-a-day meter.
Ana, 41, office staff with 10 years of SSS. She needs ₱5,000 for her son's school fees due in three weeks. She files an SSS salary loan instead of an app and pays about ₱226 a month.
Jun, 27, online seller. He wants ₱5,000 for stock that sells out every payday sale. It works only if his margin beats ₱1,220 over 61 days. He takes ₱5,000, not the ₱10,000 offered.
Mila, 50, three active loans. She wants ₱5,000 to cover another app's due date. Do not borrow. Ask the current lender about minimum payment or an extension and read what happens if you miss a payment.
Checklist before you borrow ₱5,000
- The lender's company name appears on the SEC list of recorded online lending platforms; see our legit loan apps hub.
- You see the total repayment in pesos before you sign.
- On a term of four months or less, total cost stays at or below ₱600 a month.
- You know exactly how much lands in your GCash after any deductions.
- Your due date falls on or after payday.
- You checked whether early repayment cuts the fee.
- You never pay anything upfront to "release" a loan.
Quick answers
Where can I borrow ₱5,000 online in the Philippines? Honey Loan (new clients up to ₱10,000), Cashalo (up to ₱13,000) and Tala (up to ₱25,000) publish ranges that include ₱5,000; Finbro shows your amount in the application, and Crezu matches requests from ₱500 to ₱25,000.
How much will I repay on a ₱5,000 loan? At 0.4% a day, ₱6,220 after 61 days. Under the SEC cap, a covered ₱5,000 loan can never cost more than ₱600 a month.
Can I get a ₱5,000 loan the same day? Often. Finbro says processing takes 10 minutes to 1 working day with real-time disbursement, and Honey Loan says checks usually take 2 to 3 minutes. Approval is never guaranteed.
Can I borrow ₱5,000 without a payslip? Yes. Finbro says no payslip document is required, Tala needs no income proof, and Honey Loan asks for a government ID.
Is Finbro legit? Yes. Finbro is operated by Sofi Financing Inc., SEC No. CS201908275, Certificate of Authority No. 1324, and is on the SEC list dated 20 October 2026.
What if I cannot repay ₱5,000 on time? On a covered loan, penalties are capped at 5% a month and all charges at ₱5,000. Finbro's minimum payment can push the due date 7, 14 or 30 days. Contact the lender before the due date.
Other loan amounts
Want to see more apps and bigger limits? Read our guide to the best online loan apps in the Philippines or go straight to compare offers.
Sources: SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC MC No. 14, s. 2025 as reported by GMA News (11 Dec 2025); finbro.ph homepage and FAQ (checked 31 Oct 2026); honeyloan.ph (checked 31 Oct 2026); Tala Google Play listing (updated 29 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026) and cashalo.com cash loan page; homecredit.ph cash loan FAQ (updated 31 Jul 2026) and Home Credit Google Play listing (updated 27 Oct 2026); crezu.ph (checked 31 Oct 2026); sss.gov.ph salary loan page (checked 31 Oct 2026). Cost examples are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website