Home › Blog › Lender and app reviews › Honey Loan Review 2026: Interest, Limits, Is It Legit?
Honey Loan Review 2026: Interest, Limits, Is It Legit?
Honey Loan publishes its price: 0.4% a day, up to ₱30,000 for repeat clients. We checked what that costs in pesos, what the "from 0%" claim really means and how to repay or extend.
Published November 1, 2026
The washing machine finally gave up, the repair shop quoted ₱6,500, and the next cutoff is 12 days away. You have seen Honey Loan ads promising up to ₱30,000 and "interest starting from 0%". It sounds almost too friendly for a loan app, so before you upload your ID you want three answers: is Honey Loan legit, what will it really cost in pesos, and what happens if payday comes late?
On 31 October 2026 we went through honeyloan.ph and its FAQ, apply and repay pages, its Google Play listing (updated 28 September 2026) and the SEC's list of online lending platforms. This Honey Loan review covers the published numbers, the parts that do not add up, and how to avoid overpaying.
Disclosure: Honey Loan is a partner of this site, and we may earn a referral fee if you apply. That is exactly why we list its weak points below as clearly as its strong ones.
Honey Loan at a glance
Honey Loan is an online lending platform run by Warm Cash Lending Corp. It calls itself a "responsible direct lender", so the loan is signed with Honey Loan itself. You apply on honeyloan.ph or in its Android app.
| Feature | What Honey Loan publishes |
|---|---|
| Loan amount | ₱1,000–₱30,000 |
| New clients | Up to ₱10,000 |
| Repeat clients | Up to ₱30,000 |
| Term (website) | 61–364 days |
| Daily rate | 0.4% |
| Maximum APR | 144% |
| Age | 21–70 |
| Payout | E-wallet or bank transfer |
Is Honey Loan legit?
Yes. Warm Cash Lending Corp. appears on the SEC's List of Recorded Online Lending Platforms (as of 20 October 2026) under SEC No. 2021030009095, with Honey Loan as its platform, recorded on 27 April 2021. Its website shows SEC Registration No. 2021030009095-02 and Certificate of Authority No. 3472, and links to the SEC list from its footer. For a wider view of registered apps, see our legit loan apps hub.
A few details are worth knowing, though none changes the SEC listing:
- The Google Play listing shows Certificate of Authority No. 3427, while the website says 3472. One of them is most likely a typo.
- The app is published on Google Play by DYNINNO FINTECH HOLDING LIMITED. The listing says Honey Loan is operated by Warm Cash Lending Corp.
- The website gives a Taguig (BGC) mailing address. The Play listing gives a Makati (Salcedo Village) address.
Compare the company name in your loan agreement with the SEC list; our step-by-step check shows how.
Honey Loan interest: the real cost in pesos
Honey Loan publishes its price on the homepage: a daily rate of 0.4%, a maximum APR of 144%, and "no hidden fees or commissions". Its representative example: ₱3,000 for 180 days at 12% a month costs ₱2,160 in interest and fees, so you repay ₱5,160 in six monthly installments of ₱860.
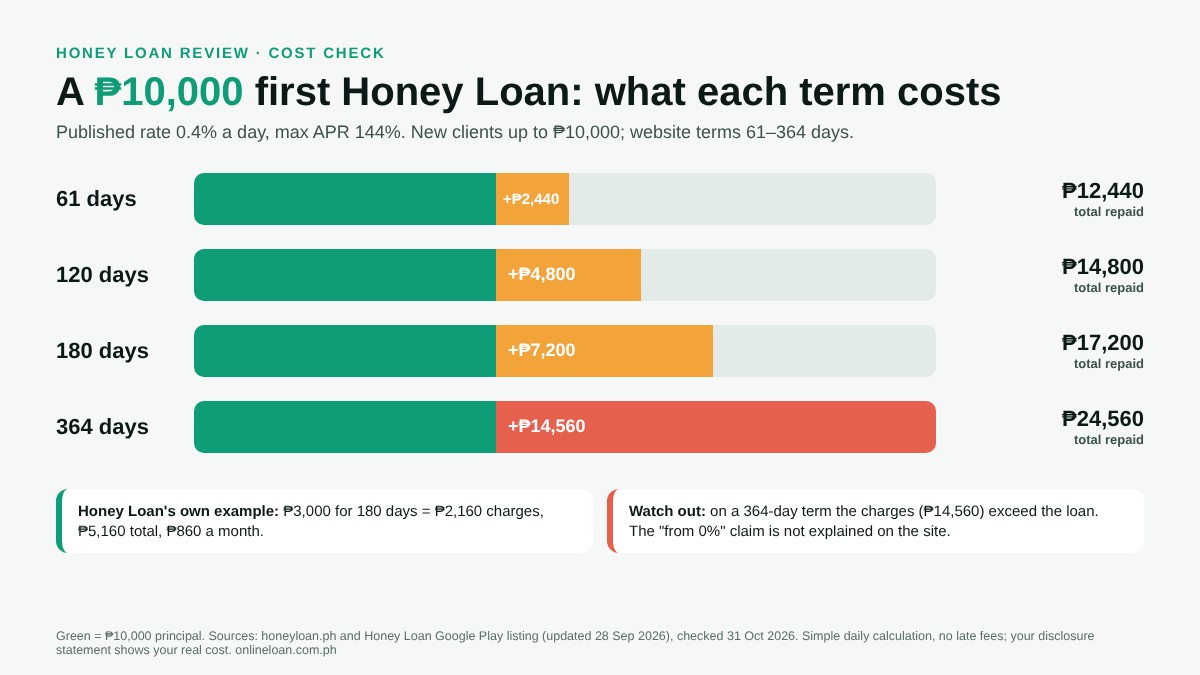
New clients can borrow up to ₱10,000, so here is what that first-loan ceiling costs at the same rate:
| Term | Charges on ₱10,000 | Total you repay |
|---|---|---|
| 61 days | ₱2,440 | ₱12,440 |
| 120 days | ₱4,800 | ₱14,800 |
| 180 days | ₱7,200 | ₱17,200 |
| 364 days | ₱14,560 | ₱24,560 |
Our calculation: amount × 0.4% × number of days, the same simple method that reproduces Honey Loan's own ₱3,000 example. No late fees included. Your exact schedule is in the disclosure statement you see before you sign.
Look at the last row. On a full-year term, the charges are bigger than the loan itself. At 12% a month, a 12-month loan costs about 144% of what you borrowed, which is exactly what the 144% APR means.
Key point. Honey Loan's long terms make each installment smaller, but the total grows every day. On ₱10,000, paying back in 61 days instead of 180 saves you ₱4,760. Use the long term only if you truly cannot repay sooner.
Where the SEC cap protects you, and where it does not
Since 1 April 2026, SEC Memorandum Circular No. 14, series of 2025, caps unsecured loans of ₱10,000 or less with terms of up to four months: total cost of no more than 12% a month, late penalties of no more than 5% a month, and all charges together no more than 100% of the loan. Honey Loan's 0.4% a day sits right at that 12% ceiling.
So a new client borrowing ₱10,000 for 61 or 120 days is inside the cap. A 180-day loan, or any repeat loan above ₱10,000, is not. A ₱30,000 repeat loan for 180 days at the same rate costs ₱21,600 in charges. Details in our 2026 interest cap guide.
What does "interest starting from 0%" mean?
Honey Loan's offers table lists new-client loans of ₱1,000 to ₱10,000, "up to 12 months", with an interest rate "starting from 0%". The website does not say who gets 0%, for how long, or on what conditions. Its published representative example and its loan terms box both use 0.4% a day.
Our honest reading: treat 0.4% a day as the real price. If a 0% promo applies to you, it will show up as a lower total in your disclosure statement before you confirm. If not, 0.4% a day is your rate, whatever the banner says. For how 0% first-loan offers usually work across the market, see our guide to zero-interest first loans.
Honey Loan requirements and how to apply
The homepage lists four basics: you are a Filipino citizen aged 21 to 70, you have a valid government ID, your mobile number is active and not blocked, and you register on the website. The how-to-apply page adds a selfie and says no guarantor or payslip is needed. If you choose a bank transfer, the account must be in your name.
- Register at honeyloan.ph or in the app with your mobile number.
- Fill in the form with your personal details. The site says it takes up to 7 minutes.
- Upload your valid ID and a selfie.
- Wait for the SMS decision. The site quotes approval in "as little as 2 minutes" in one place and "processing in 5 minutes" in another. The lender may also call you.
- Read the disclosure statement, then claim the money to your e-wallet or bank.
One thing to check on screen: when we opened the homepage calculator on 31 October 2026, it showed a first repayment date of 8 November 2026 for a new-client loan, about a week away, even though terms start at 61 days. Look at your full repayment schedule, not just the term, so the first installment does not catch you off guard.
How to repay Honey Loan, and the minimum payment option
Log in at honeyloan.ph with your registered mobile number, confirm with the SMS code, then choose "Make full repayment" or "Make min payment". Payments run through Dragonpay, using your Repayment Lifetime ID as the reference. The repayment page lists:
- QR PH, from your bank or e-wallet app
- GCash and Maya, under Bills, via Dragonpay
- Online banking via Dragonpay
- Over the counter, cash only: 7-Eleven CLIQQ, ECPay, Bayad Center, Cebuana Lhuillier, LBC, M Lhuillier, Palawan Express and more
At a counter, say it is a bills payment to Dragonpay, not a remittance.
The page also says you can repay the whole loan on or before the next payment date "without any additional costs". If you cannot pay in full, a minimum payment moves your next payment date by 7, 14 or 30 days. That is useful breathing room, but understand what you are buying: some Google Play reviewers say their minimum payments did not reduce the balance they owed. Honey Loan does not publish how a minimum payment is split, so before you use it, check in your account how much of it, if any, goes to the principal.
What we could not find: late fees. The FAQ sections on repayment show no content, and the Terms and Conditions and Disclosure Statement are mentioned but not linked on the public pages. For loans inside the SEC cap, penalties cannot exceed 5% a month on the overdue amount. If you are already behind, read what to do after a missed loan payment.
Honey Loan pros and risks
| Pros | Risks |
|---|---|
| Price and example published | 0% claim not explained |
| Up to ₱30,000 for repeat clients | Late fees not published |
| Minimum payment: +7, 14 or 30 days | Long terms can cost over 100% |
| Early repayment at no extra cost | Small details differ across pages |
| Many repayment channels | Age 21 to 70 only |
Real scenarios
Paolo, 26, warehouse staff, ₱6,500 for the washing machine. First loan, so his ceiling is ₱10,000. He picks 61 days. At 0.4% a day the charges are ₱1,586, total ₱8,086. If he clears it early on his second payday, he pays less.
Maricel, 44, sari-sari store owner, repeat client. Her limit is now ₱20,000, but she needs only ₱8,000 for restocking. She borrows ₱8,000 for 120 days, which keeps the loan inside the SEC cap. Charges: ₱3,840, total ₱11,840. The rest of her limit stays unused.
Kevin, 31, freelancer, client payment delayed. He cannot pay in full on the due date, so he makes a minimum payment for a 14-day extension and checks what balance is left.
When not to borrow. If only the 364-day term makes the installment affordable, the loan is probably too big.
Honey Loan vs Cashalo
Both publish the same price: 0.4% a day and a 144% maximum APR. The difference is room. Cashalo, on its Play listing of 12 October 2026, goes up to ₱13,000 with terms of 61 to 180 days, and its repayment page does not mention a minimum payment. Honey Loan goes up to ₱10,000 for new clients and ₱30,000 for repeat clients, and offers a minimum payment extension. Cashalo's app, though, is far more established on Google Play, with 10M+ downloads against Honey Loan's 100K+. Our Cashalo review covers it in detail.
Ready to see your Honey Loan offer? Check the amount and the total repayment before you confirm. Applying does not oblige you to accept.
Check Honey LoanAlternatives to Honey Loan
- Warm Cash Lending Corp., on the SEC list
- 0.4% a day, maximum APR 144%
- Minimum payment moves your date 7, 14 or 30 days
- Late fees not published on the site
- Sofi Financing Inc., SEC No. CS201908275
- Minimum payment option to move your due date
- Rate is shown only during the application
- Free to use, no service fee from Crezu
- Terms of 91 to 120 days, per its site
- Not a lender: check who approves you
Checklist before you accept a Honey Loan offer
- Borrow the amount you need, not your full limit.
- Check that the total in the disclosure statement matches 0.4% a day, or is lower if a 0% promo applies.
- Note the first repayment date, not just the term.
- Stay at ₱10,000 or less and 4 months or shorter if you want the SEC cap to apply.
- Ask support (02-8876-1972, 9 AM to 6 PM) about late fees before you sign.
- If you plan to use a minimum payment, check how much goes to the principal.
- Pay through GCash, Maya or QR PH and keep the receipt.
Quick answers
Is Honey Loan legit? Yes. Warm Cash Lending Corp. (Honey Loan) is on the SEC's list of recorded online lending platforms as of 20 October 2026, SEC No. 2021030009095.
What is Honey Loan's interest? 0.4% a day, with a maximum APR of 144%. ₱3,000 for 180 days costs ₱2,160, so you repay ₱5,160.
How much can I borrow from Honey Loan? ₱1,000 to ₱10,000 on your first loans, and up to ₱30,000 as a repeat client.
What are the Honey Loan requirements? Filipino citizen aged 21 to 70, a valid government ID, a selfie and an active mobile number. No payslip or guarantor, says its site.
Is Honey Loan really 0% interest? The site says new-client rates start "from 0%" but does not explain when. Plan for 0.4% a day unless your disclosure statement shows less.
Can I extend my Honey Loan due date? Yes. A minimum payment moves your next payment date by 7, 14 or 30 days. Early full repayment has no extra cost.
Not sure yet? Compare offers from other lenders and pick the one with the lowest total you can repay on time.
Sources: honeyloan.ph homepage, FAQ, how-to-get-loan, how-to-repay-loan and about pages (checked 31 Oct 2026); Honey Loan Google Play listing, com.dyninno.mobileapp.philippines (updated 28 Sep 2026, checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026), as summarized on cashalo.com; Cashalo Google Play listing (updated 12 Oct 2026); finbro.ph FAQ and crezu.ph homepage (checked 31 Oct 2026). Peso examples other than Honey Loan's own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Honeyloan?
Honeyloan
Compare available lending offers
Review the final repayment amount and terms on the provider's website