Home › Blog › Loans by amount and term › ₱10,000 Loan Online Philippines: Borrow 10k Safely
₱10,000 Loan Online Philippines: Borrow 10k Safely
₱10,000 is the exact edge of the SEC small-loan cap. Borrow it the right way and every peso of interest and fees stays limited by law.
Published November 1, 2026
The landlord wants the advance and deposit for the new room by Saturday, and you are ₱10,000 short. Or your father's lab tests cannot wait for the 30th. ₱10,000 is too much to borrow from a friend without awkwardness.
It is also a legal borderline. ₱10,000 is the exact upper edge of the 2026 SEC small-loan cap, which only protects unsecured loans of ₱10,000 or less with terms of up to four months. Borrow ₱10,000 for 120 days and every peso of interest, fees and penalties is capped. Borrow ₱10,500, or pick a six-month term, and the cap stops applying. Below: where to borrow ₱10,000, what it costs, and why the amount and term you tap matter as much as the app.
Try a different amount or term in the calculator below. It starts at ₱10,000 for 90 days and uses a general illustrative rate, not a quote from Crezu or any lender it works with; the lender's disclosure statement shows your real figure, and the tables below use published rates.
Estimate your Crezu repayment
Illustrative only — the lender sets the final rate. Crezu sets your actual rate, fees and schedule and shows them on its own site before you sign. This is an illustration, not an offer.
Where to borrow ₱10,000 online
Each card publishes a range that includes ₱10,000, except Finbro, which shows your offer in the application. Partners and benchmarks are marked.
- Warm Cash Lending Corp., on the SEC list
- 0.4% a day, maximum APR 144%
- Repeat clients can go up to ₱30,000
- Age 21 to 70, terms from 61 days
- Free for you, terms of 91 to 120 days
- Valid PH ID and a bank account
- Not a lender: check who approves you
- 1 valid ID, no income proof
- Up to 120 days, repay any time
- Processing fee ₱399–₱999 on ₱10,000
- Paloo Financing, Inc., on the SEC list
- 12% monthly rate on covered loans, it says
- Up to ₱13,000 only "for good-paying customers"
- 2.49%–8.49% a month, 6 to 48 months
- Processing fee 3%, max ₱1,000
- Only with an existing offer
- Sofi Financing Inc., SEC No. CS201908275
- Minimum payment moves the due date 7, 14 or 30 days
- Amount and rate shown only in the application
The ₱10,000 line: what changes at ₱10,500 or 6 months
SEC Memorandum Circular No. 14, series of 2025, in force since 1 April 2026, caps charges on unsecured, general-purpose loans of ₱10,000 or less with terms up to four months: interest at most 6% a month, interest plus fees at most 12% a month, late penalties at most 5% a month, and all charges together never more than the principal. On ₱10,000 that means:
| Charge on ₱10,000, up to 4 months | Legal maximum |
|---|---|
| Interest | ₱600 a month |
| Interest plus all fees | ₱1,200 a month |
| Late penalty | ₱500 a month on ₱10,000 overdue |
| Everything, however late | ₱10,000 |
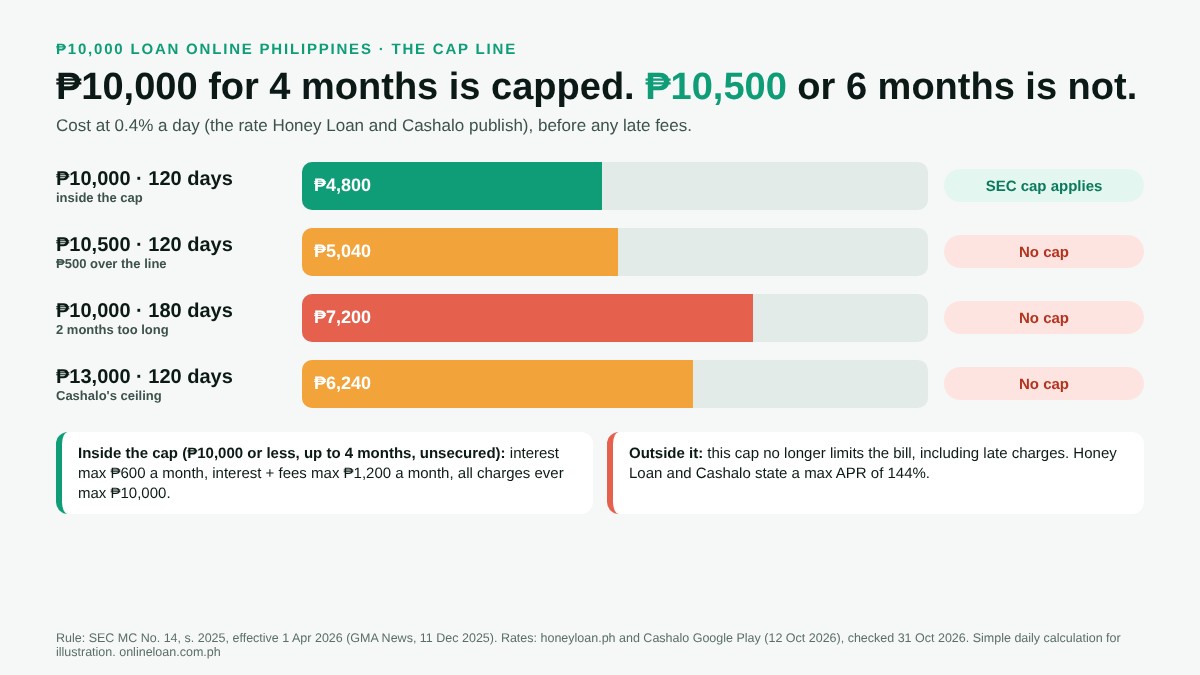
Now change one thing at a time. At the same 0.4% a day that Honey Loan and Cashalo publish:
| Loan | Cost at 0.4% a day | SEC cap applies? |
|---|---|---|
| ₱10,000 for 120 days | ₱4,800 | Yes |
| ₱10,500 for 120 days | ₱5,040 | No |
| ₱10,000 for 180 days | ₱7,200 | No |
| ₱13,000 for 120 days | ₱6,240 | No |
The extra ₱500 costs only ₱240 more at the same rate. The real change is protection: above ₱10,000 or beyond four months, the legal 12%-a-month ceiling and the "charges never exceed the principal" rule no longer cover you. Honey Loan and Cashalo still state a maximum APR of 144%, but late charges are no longer bounded by this rule. Our rate cap explainer has the details.
Key point. If ₱10,000 solves the problem, borrow ₱10,000, not ₱10,500, and keep the term at 120 days or less. That one choice keeps every peso of interest, fees and penalties under a legal ceiling.
Need ₱10,000 within the cap? Compare partner offers for ₱10,000 and check the term before you confirm.
Compare offersHow much does a ₱10,000 loan really cost?
| Option for ₱10,000 | Cost | Total |
|---|---|---|
| Honey Loan / Cashalo, 61 days | ₱2,440 | ₱12,440 |
| Honey Loan / Cashalo, 90 days | ₱3,600 | ₱13,600 |
| Tala, 61 days (11–12% a month) | ₱2,237–₱2,440 | ₱12,237–₱12,440 |
| Home Credit, 12 months at 2.49% | about ₱1,691 + fee | about ₱974 a month |
| Crezu's own example, 3 months | ₱5,000 | ₱15,000 |
How we calculated. The 0.4% rows are ₱10,000 × 0.4% × days; for Tala we applied its published 11–12% monthly effective rate over 61 days. The Home Credit row amortizes ₱10,000 at its lowest published rate of 2.49% a month over 12 months, the same method its own ₱15,000 example uses (₱1,461 a month, ₱17,537 total); its 3% processing fee adds ₱300 and is deducted from the proceeds. Higher rates up to 8.49% a month cost much more, and a 12-month loan is outside the SEC cap.
About Crezu's example
Crezu's site gives a sample of ₱10,000 over 3 months with a total of ₱15,000. That is ₱5,000 in cost, about 16.7% a month, which does not match the 12%–36% APR range it states on the same page. It is also above what a lender may charge on a covered ₱10,000 loan: the cap allows at most ₱3,600 in interest and fees over three months. Crezu is not the lender; your real price comes from the lender it connects you with. If an offer for ₱10,000 over three months shows more than ₱13,600 to repay before any late fees, do not sign; check the lender in our legit loan apps hub.
How to get ₱10,000 online in 4 steps
- Pick a lender you can verify. Look up the company name on the SEC list; our two-minute guide shows how.
- Prepare one valid ID and a selfie. A higher amount can mean extra checks; see our documents guide and tips to improve approval chances.
- Set exactly ₱10,000 and a term of 120 days or less. Read the disclosure statement: total repayment, installment dates and anything deducted upfront.
- Choose your payout. Honey Loan, Finbro and Cashalo list GCash, Maya or bank; Crezu asks for a bank account.
Who can borrow ₱10,000?
Honey Loan accepts Filipino citizens aged 21 to 70 with a government ID and an active mobile number, and ₱10,000 is the most it lends on a first loan. Tala accepts resident citizens 18 and up and sets your limit between ₱1,000 and ₱25,000. Finbro wants citizens aged 20 to 70 with a regular income and says no payslip document is required. Home Credit cash loans are for existing customers who already have an offer.
Real scenarios: ₱10,000, yes or no?
Grace, 29, moving for a new job. She needs ₱10,000 for the room deposit, and her first salary arrives in five weeks. A 61-day loan at 0.4% a day costs ₱2,440; she repays in two halves and stays inside the cap.
Ramon, 38, tricycle driver. He needs ₱10,500 for a part. He pays ₱500 from savings and borrows ₱10,000, so the cap covers him.
Liezl, 45, wants 6 months to pay. 180 days at 0.4% a day costs ₱7,200. She has a Home Credit offer: six monthly installments on a declining balance cost about ₱889 at 2.49% a month or ₱3,172 at 8.49%, plus the ₱300 fee. Without an offer, that door is closed.
Paolo, 24, wants ₱10,000 for a new phone on sale. Not a good loan: up to ₱4,800 in charges turns a discount into a premium.
Cheaper ways to find ₱10,000
If you have years of SSS contributions, the SSS salary loan charges 8% a year plus a 1% fee, repaid over 24 months, but it is not same-day. Ask your employer about a salary advance. For wallet-based credit, see our GCash loans guide, and for pawnshops and banks, read apps vs banks vs pawnshops.
Checklist before you borrow ₱10,000
- The amount is ₱10,000 or less and the term is four months or less, if you want the cap to protect you.
- The lender's company name is on the SEC list of recorded online lending platforms.
- Interest plus fees stay within ₱1,200 a month.
- You know how much actually lands in your account after deductions.
- Your installment dates match your paydays.
- You checked whether paying early lowers the cost.
- You never pay a "release fee" before getting the money.
Quick answers
Where can I borrow ₱10,000 online in the Philippines? Honey Loan lends up to ₱10,000 to new clients, Cashalo up to ₱13,000, Tala up to ₱25,000, and Home Credit from ₱3,000 for customers with an offer. Crezu matches requests from ₱500 to ₱25,000.
How much will I repay on a ₱10,000 loan? At 0.4% a day, ₱12,440 after 61 days or ₱13,600 after 90 days. Under the SEC cap, a covered ₱10,000 loan can cost at most ₱1,200 a month in interest and fees.
Can I get ₱10,000 the same day? Sometimes. Honey Loan says checks usually take 2 to 3 minutes and Finbro says disbursement is real-time after approval, but the amount offered can be lower than ₱10,000 and approval is never guaranteed.
Can I borrow ₱10,000 without a payslip? Yes, at some lenders. Finbro says no payslip document is required, Tala asks for no income proof, and Honey Loan asks for a government ID.
Is Crezu legit? Crezu is a brand of Fininity OÜ, registered in Estonia, and says it is an intermediary, not a lender. It does not lend, so check the lender it connects you with on the SEC list. Read our Crezu review.
What if I cannot repay ₱10,000 on time? On a covered loan, penalties are capped at 5% a month and all charges at ₱10,000. Talk to the lender before the due date, and read what happens if you miss a payment.
Other loan amounts
Need more than ₱10,000? Our guide to the best online loan apps in the Philippines covers higher limits, or go straight to compare offers.
Sources: SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC MC No. 14, s. 2025 as reported by GMA News (11 Dec 2025); honeyloan.ph (checked 31 Oct 2026); crezu.ph (checked 31 Oct 2026); Tala Google Play listing (updated 29 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026) and cashalo.com cash loan page; Home Credit Google Play listing (updated 27 Oct 2026) and homecredit.ph cash loan FAQ (updated 31 Jul 2026); finbro.ph homepage and FAQ (checked 31 Oct 2026); sss.gov.ph salary loan page. Cost examples are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Crezu?
Crezu
Compare available personal loan options online
Review eligibility, repayment amount, interest, fees and all terms on the provider's website before applying