Home › Blog › Lender and app reviews › Crezu Review Philippines: Is Crezu Legit?
Crezu Review Philippines: Is Crezu Legit?
Crezu is not a lender but a free matching service. Here is how it works, what its own example really costs and how to check the lender it sends you to.
Published November 1, 2026
You got declined by one app on Monday and another on Wednesday. Then an ad pops up: "1st Credit with 0%", ₱500 to ₱25,000, decision in 2 minutes. The site is called Crezu, and it does not look like the loan apps you know. Is it a lender? Is it safe to type your ID and bank details into it? And what will you actually pay?
This Crezu review answers that from Crezu's own Philippine website, its Terms of Use and its Privacy Policy, all opened on 31 October 2026. Short version: Crezu is not a lender. It is a free matching service that passes your details to partner lenders. That can save you time, but the lender it sends you to decides your price, and Crezu's own cost example is far higher than the rate range it advertises.
Disclosure: Crezu is a partner of this site, and we may earn a referral fee if you apply through our link. It does not change the numbers below.
Crezu at a glance
| Item | What crezu.ph says |
|---|---|
| What it is | Loan matching service |
| Company | Fininity OÜ, Estonia |
| Loan amount | ₱500 to ₱25,000 |
| Term | 91 to 120 days |
| Rates | 12% to max APR 36% |
| Fee to you | None from Crezu |
| You need | Phone, PH ID, bank account |
Crezu is a brand of Fininity OÜ, registration number 14523902, with its office in Haabneeme, Estonia. Its homepage says plainly: "This site is not a financial institution, bank, or lender." Its Terms add that it will "never provide financing directly to you."
How Crezu works, step by step
- Fill in one form. You start with your phone number and then add personal, income and bank details.
- Crezu sends it to partners. Your application goes to lenders and brokers in its network. Some may run a soft credit check.
- Compare and pick. If lenders accept, you see their offers and choose one.
- Sign with the lender. You sign the lender's own loan agreement, and the money goes to your bank account.
Crezu does not charge you for any of this. Its Terms say it "may be paid a fee by the Lender or Provider for connecting you to them." There is no obligation to accept any offer.
Speed claims on the homepage vary. It mentions "Decision in 2 min" and money "in 15 min" in one place, and approval in "Up to 7 minutes" elsewhere. Approval rate claims also differ: "Up to 90%" in the hero and "95%" further down. Treat these as marketing. The Terms say Crezu "cannot and will not guarantee" that any lender will approve you.
Declined once already? Crezu sends one free form to several partner lenders. Check who answers, then compare the total to repay.
Compare offers via CrezuCrezu interest: the example that does not add up
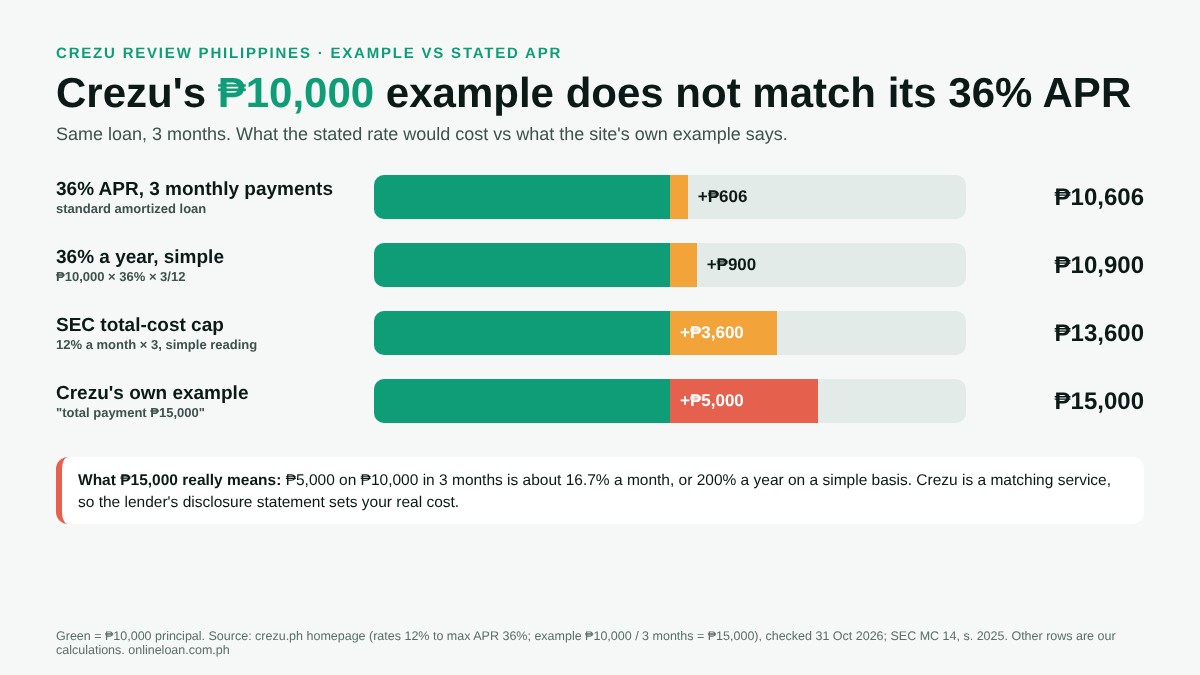
Crezu's homepage says lender rates "vary from lender to lender in the range from 12% to a maximum APR of 36%." A few lines later it gives this example: "for a loan of ₱10,000 that will be paid in 3 months, the total payment of the loan will be ₱15,000." Those two statements cannot both describe the same loan.
| ₱10,000 for 3 months | Extra cost | Total repaid |
|---|---|---|
| 36% APR, 3 monthly payments | ₱606 | ₱10,606 |
| 36% a year, simple | ₱900 | ₱10,900 |
| SEC cap, 12% a month | ₱3,600 | ₱13,600 |
| Crezu's own example | ₱5,000 | ₱15,000 |
Our math, done in Python. At the stated maximum of 36% a year, simple interest on ₱10,000 for 3 months is ₱10,000 × 36% × 3/12 = ₱900. Paid in three equal monthly installments at 3% a month, each payment is about ₱3,535, or ₱10,606 in total. Crezu's ₱15,000 example means ₱5,000 in charges over 3 months: about 16.7% a month, or 200% a year on a simple basis. If you repay it in three equal payments of ₱5,000, the effective rate works out to roughly 23% a month.
There is also a legal angle. Under SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026), unsecured loans of ₱10,000 or less with terms of up to four months are capped at a total cost of 12% a month. On a simple reading, that allows at most about ₱3,600 in charges on ₱10,000 over 3 months. Crezu's example sits above that line. Our interest rate cap explainer covers the rule.
What does this mean for you? Probably that the example is an outdated or generic illustration, not a real quote. But it is a good reminder that the 12% to 36% range is not a promise. Your real price is the one in the lender's disclosure statement. Read our guide to online loan interest rates to spot the total in pesos.
Key point. Ignore every rate on a matching site, including "0%" and "36%". The only number that counts is the total amount to repay in the lender's disclosure statement. If it is above ₱13,600 on a ₱10,000, 3-month loan, ask why before you sign.
What about "1st Credit with 0%"?
The homepage headline shows "1st Credit with 0%" and an interest rate of "0%*". The footnote says only: "First loan can be free of charge for new clients." No amount, term or lender is named. Some partner lenders may offer a free first loan, but Crezu cannot promise it. We explain how these promos usually work, and how much it costs if you miss one, in our guide to the 0% interest first loan.
Is Crezu legit?
Crezu is a real, named company: Fininity OÜ, registered in Estonia (No. 14523902), with published Terms, a Privacy Policy, a complaints address and a data-protection contact. Its Terms are governed by Philippine law. It is not a lender, so it does not appear on the SEC's List of Recorded Online Lending Platforms, and it does not need to for the matching itself. The lender you end up with does.
How to check the lender Crezu sends you to
- Before signing, note the lender's full company name from the offer or loan agreement, not just the app or brand name.
- Open the SEC's List of Recorded Online Lending Platforms (latest version we checked: 20 October 2026) and search for that company name and its brand.
- Match the SEC registration number and Certificate of Authority number on the lender's own site with the list.
- If the company is not on the list, do not sign. If anyone asks for a fee before releasing the loan, walk away.
Our step-by-step SEC check guide has screenshots, and the legit loan apps hub lists registered apps.
What data Crezu collects and who sees it
Crezu's Privacy Policy, marked "Last updated October 2019", says it processes data under the Philippine Data Privacy Act of 2012 (RA 10173). It lists what it collects:
- Name, address, residential status and birthdate
- Email address and phone number
- Income, employer details and bank account details
- IP address, pages you view and the site you came from
- Your loan requests and anything you write in emails to them
It shares this with lenders and credit brokers to get you quotes, with other panel providers that may run fraud and credit reference checks, and with an advertising partner (Ezoic) for interest-based ads. The policy also lists marketing about other products and passing data to third parties for marketing among its purposes. It says it accepts "no responsibility" for how a lender uses your data once shared. Application data is kept "for a minimum period of 6 years".
Unsubscribe and data deletion
The policy gives you the right to access, correct and erase your data, and to object to marketing. It says marketing objections are handled within 48 hours and erasure requests within 72 hours, subject to legal retention. To unsubscribe or ask for deletion, use the GDPR form linked in the site footer (unsub.crezu.com, while the policy uses unsub.crezu.net) or email compliance@crezu.net. Complaints go to complaints@crezu.net. Remember that lenders who already received your data hold it under their own policies, so contact them too.
Crezu pros and risks
Pros
- Free to use, with no service fee charged to you.
- One form reaches several lenders, useful after a decline.
- Small amounts from ₱500 and terms of 3 to 4 months.
- Real company name, Terms, Privacy Policy and deletion route published.
Risks
- Not a lender: the price and approval depend on a partner you only meet at the end.
- Its ₱15,000 example contradicts its own 36% APR ceiling.
- "0%" and approval rates are not backed by named conditions.
- Your data goes to several lenders and an ad network, and marketing messages are likely.
- Privacy Policy and Terms dated October 2019.
Real scenarios
Rina, 29, needs ₱6,000 for a laptop repair. Two apps turned her down. She fills one Crezu form, gets two offers and checks both lenders on the SEC list. One is not on it, so she drops it. Say the other prices it at 0.4% a day: ₱6,000 over 120 days would mean ₱8,880 to repay, so she compares that with a direct lender before deciding.
Ben, 35, wants exactly ₱10,000 for three months. He sees "36%" and budgets ₱10,900. The offer he gets shows a higher total. Because he read the disclosure statement first, he asks the lender to explain the fees and picks a shorter term instead.
Joy, 24, just wants to compare without spam. A matching service is not ideal for her. If she does use one, she unsubscribes right after choosing a lender and requests deletion through the form linked in Crezu's footer.
Checklist before you accept a Crezu offer
- Write down the lender's full company name.
- Find it on the SEC list of 20 October 2026 or later.
- Read the total to repay in pesos, not the APR.
- On ₱10,000 or less for up to 4 months, check charges stay within 12% a month.
- Confirm the full amount is released with no upfront fee.
- Note the due dates and the late-payment terms.
- Unsubscribe from marketing if you do not want more offers.
Alternatives to Crezu
If you would rather sign directly with a lender, or compare with other matching services, these are partners of this site.
- Warm Cash Lending Corp., SEC No. 2021030009095
- 0.4% a day, max APR 144%
- New clients capped at ₱10,000
- Sofi Financing Inc., SEC No. CS201908275
- Minimum payment moves due date 7, 14 or 30 days
- Rate shown only during the application
- Free to compare offers
- Not a lender: check who approves you
Quick answers
Is Crezu legit in the Philippines? Crezu is a real matching service run by Fininity OÜ, registered in Estonia, with published Terms and a Privacy Policy. It is not a lender, so always check the lender it connects you with on the SEC's list.
Is Crezu a lending company? No. Its site says it "is not a financial institution, bank, or lender". It passes your application to partner lenders.
How much can I borrow through Crezu? Crezu lists ₱500 to ₱25,000, repaid over 91 to 120 days. The lender decides your actual amount.
What interest does a Crezu loan charge? Crezu states 12% to a maximum APR of 36%, but its own ₱10,000 example totals ₱15,000 in 3 months. Rely on the lender's disclosure statement.
Does Crezu charge a fee? Crezu says it charges no service fee. It may be paid by the lender for the referral.
How do I delete my data from Crezu? Use the GDPR unsubscribe form linked in its footer or email compliance@crezu.net. Its policy says erasure requests are handled within 72 hours, subject to legal retention.
Prefer to see everything side by side? Compare offers from all partners in one place.
Sources: crezu.ph homepage, Terms of Use and Privacy Policy (checked 31 Oct 2026; policies marked "Last updated October 2019"); SEC List of Recorded Online Lending Platforms as of 20 October 2026; honeyloan.ph and finbro.ph details as checked for our reviews on 31 Oct 2026; SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026). Calculations other than Crezu's own example are ours. This article is general information, not legal or financial advice.
Ready to check your offer with Crezu?
Crezu
Compare available personal loan options online
Review eligibility, repayment amount, interest, fees and all terms on the provider's website before applying