Home › Blog › Lender and app reviews › BillEase Review: Cash Loan, Pay Later and Real Costs
BillEase Review: Cash Loan, Pay Later and Real Costs
BillEase is a registered pay-later and cash loan app with 0% promos and a 3.49% monthly rate. Here is what each product really costs in pesos, and when it is worth using.
Published October 29, 2026
You are at checkout, the phone you want costs ₱12,000, and there it is: a "Pay with BillEase" button promising small monthly payments. Or it is the 23rd, payday is a week away, and you need ₱5,000 in GCash today. BillEase wants to be the app you open in both moments.
It is a big one. BillEase has more than 10 million downloads and about 242,000 reviews on Google Play, where it sits at 4.7 stars as of 29 October 2026. But "pay later" is still borrowing, and the price depends on which of its three products you use: a cash loan, a merchant installment or the newer Credit line.
This review breaks down each one in plain pesos, shows where BillEase is cheap and where it is not, and tells you what to check before you tap "confirm".
Is BillEase legit?
Yes. BillEase is run by First Digital Finance Corporation (SEC No. CS201516347), a financing company with Certificate of Authority No. 1101. The company is on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026, with three registered platform names: Billease, Balikbayad and FDFC. It is also registered with the Bangko Sentral ng Pilipinas as an operator of payment systems (OPSCOR-2021-0007).
It is not a fly-by-night app either. According to Philstar (11 June 2026), the company earned ₱840 million in net profit in 2025 on ₱9.3 billion in revenue, and it is putting ₱1 billion into its own rural bank, the former Rural Bank of Sta. Maria in Ilocos Sur. Legit, however, only means it is allowed to lend. Whether a given loan is a good deal is a separate question, and that is what the rest of this review is about. For a wider list of registered apps, see our guide to legit loan apps in the Philippines.
BillEase at a glance
| Feature | BillEase |
|---|---|
| Operator | First Digital Finance Corp. · SEC No. CS201516347 |
| Loan amounts | ₱500–₱50,000 |
| Terms | 2–24 months |
| Monthly interest | 0%–3.49% (app listing) · 0%–5% (website) |
| Service charge | 0%–10% |
| Credit line | ₱10,000–₱50,000 · up to 62 days interest-free |
| Requirements | 18+, stable income, one valid government ID |
| Google Play | 4.7 stars · 242K reviews · 10M+ downloads |
Sources: BillEase Google Play listing, website and FAQ, checked 29 October 2026.
Notice the interest line. The Google Play listing says monthly interest runs from 0% to 3.49%, while the BillEase homepage says 0% to 5%. Neither page explains which products get which rate, so treat 3.49% as the usual figure and the disclosure statement in your app as the final word.
Three products, three different price tags
Most confusion about BillEase comes from mixing up its products. They have separate limits, and using one does not reduce the other.
1. Cash loan: money to your bank or e-wallet
This is the "I need ₱5,000 in GCash" product. Your loan limit can be sent to a bank account or e-wallet, or used for mobile load and bills. Each draw becomes a separate loan with fixed monthly installments. This is the most expensive way to use BillEase, because you pay both interest and a service charge.
2. Merchant installment: pay later at a partner store
This is the checkout button. BillEase says it works with more than 10,000 partner merchants, including Samsung, Agoda, Philippine Airlines, Mandaue Foam and Power Mac Center. Merchant loans run up to 24 months and are calculated on a declining balance, so extra payments go straight to principal and there is no penalty for paying early. Some merchants offer 0% interest promos, which is where BillEase is at its cheapest.
3. Credit line: a credit card without the card
The newest product works like a credit card. You scan QR Ph codes at more than 600,000 merchants, or tap the BillEase Access Card, and get one monthly statement. Limits currently run from ₱10,000 to ₱50,000. If you pay the full statement by the due date, all interest is waived, which can mean up to 62 days of free credit. There is no processing fee and no annual fee. The catch: it cannot be cashed out or sent to a wallet.
What a BillEase cash loan really costs
BillEase's own example on Google Play is a ₱12,000 cash loan over three months. You receive the full ₱12,000 with nothing deducted upfront, then pay three installments of ₱4,539. Each one is ₱4,000 principal, ₱419 interest and ₱120 service charge, for a total of ₱13,617.
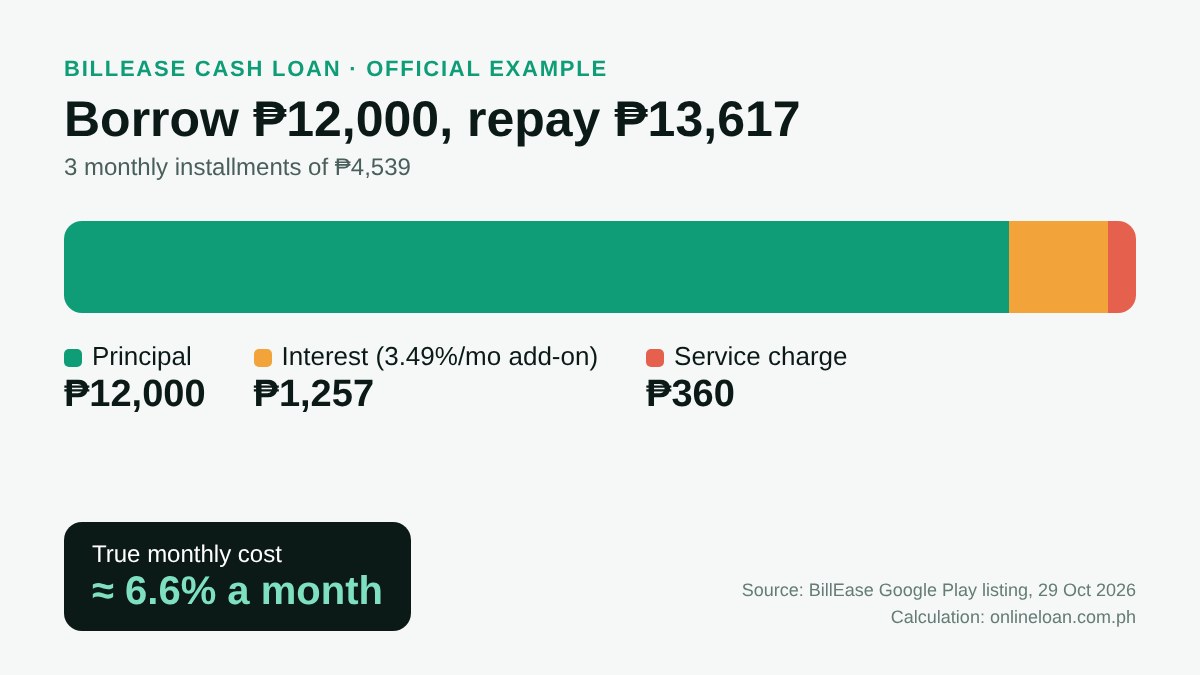
One small slip on that listing: it labels the total service charge as ₱420, but three charges of ₱120 add up to ₱360, and only ₱360 matches the ₱13,617 total. It is a typo, but it is a good reminder to check the math on any loan screen.
The interest is "add-on", which means 3.49% of the original ₱12,000 is charged every month, even as your balance shrinks. That is why the true monthly cost is higher than 3.49%. Here is what the same structure looks like on other amounts:
| Loan and term | You repay | True monthly cost |
|---|---|---|
| ₱12,000 · 3 months (official example) | ₱13,617 · 3 × ₱4,539 | About 6.6% |
| ₱5,000 · 3 months | ₱5,673.50 · 3 × ₱1,891.17 | About 6.6% |
| ₱10,000 · 6 months | ₱12,694 · 6 × ₱2,115.67 | About 7.3% |
| ₱12,000 · 0% merchant promo | ₱12,000 | 0% |
How we calculated: rows two and three use the same formula as BillEase's example, 3.49% monthly add-on interest plus a 1% monthly service charge on the original amount, paid in equal monthly installments. The true monthly cost is the rate at which those payments repay the loan, worked out with code. Your actual rate and service charge may differ, so check your offer.
About 6.6% a month works out to roughly 79% a year if you simply multiply by 12. That is far below what many short-term loan apps charge, and it is well within the SEC's 2026 ceiling of 12% a month effective interest for small loans. But it is not the "lowest rate" feeling that a 3.49% headline suggests. Our explainer on how online loan interest rates work shows why add-on rates always look smaller than they are, and our guide to the 2026 interest rate cap explains which loans the ceiling covers.
Key point. BillEase is cheap when you use a 0% merchant promo or pay your Credit line in full every month. Its cash loan is a different story: the 3.49% monthly rate is add-on interest, and with the service charge the true cost of BillEase's own ₱12,000 example is about 6.6% a month.
Real-life scenarios: which product fits?
"I want a ₱15,000 phone and the store has a 0% promo." This is BillEase's sweet spot. If the price is the same as paying cash and there is no processing fee, you are borrowing for free. Just check that the "promo" price is not higher than the store's regular cash price.
"Payday is in a week and I need groceries and medicine." If you have the Credit line, pay by QR Ph and settle the full statement on time. Even regular QR Ph payments default to a one-time payment on your next payday at 0% interest. Miss that due date, though, and late interest of 5% a month, charged daily, kicks in.
"I need ₱5,000 cash for rent." The cash loan works, but expect to repay about ₱5,670 over three months on the structure above. Compare that with other registered options first, including GCash loans like GLoan and GGives if you already use GCash.
Applying: what BillEase asks for
The requirements are light. You need to be at least 18, have a stable source of income and scan one valid government ID in the app. BillEase says proof of billing and payslips are usually not needed, though it may ask for more documents. Freelancers can apply.
Approval can be instant or take up to a day. Applications sent after 6:00 PM are treated as next-day submissions. Expect a modest first limit. BillEase says borrowers who pay on time can get higher limits and longer terms, and some Google Play reviewers say their limit went up after each loan they paid off.
Not every review is happy. One September 2026 review on Google Play complains that a limit dropped from ₱41,350 to ₱27,000 after a loan was finished, and another notes that the first due date comes in less than a month. These are individual reports we cannot verify, but they are a fair warning: your limit is not guaranteed and can change.
Paying back, and what happens if you are late
You can pay through the app's Pay Now options, including QR Ph, InstaPay or PESONet transfers, bank deposits and over-the-counter at 7-Eleven, Cebuana and M Lhuillier outlets, according to the Google Play listing.
If you cannot pay on time, BillEase's FAQ says to contact it on or before the due date, when a "discounted charge" may be available. After that, late penalties may apply and your credit score can be affected. BillEase does not publish a single late-fee rate for cash loans; the only figure in its FAQ is 5% a month, charged daily, for overdue QR Ph payments. For Credit line users, missing the minimum due locks your limits and starts daily delinquency interest. Collection fees can apply if field visits become necessary.
On collection, BillEase's website says it will not contact your family, employer or phone contacts. If any collector does, that breaks SEC rules, and our guide on what happens if you miss a loan payment explains what you can do about it.
Watch out for fake "BillEase agents"
BillEase's own scam page is worth reading, because its name is widely copied. The key rules it lists:
- BillEase never asks for your OTP, PIN or password, by any channel.
- A text that shows "BILLEASE" as the sender proves nothing, and BillEase does not send links by text.
- Pay only through Pay Now in the app. Never pay a sales agent, a personal e-wallet or a personal QR code.
- Sellers who offer to turn your limit into cash for a cut are not allowed, and you still owe the full amount.
Pros and risks
| Pros | Risks |
|---|---|
| On the SEC list dated 20 Oct 2026 | Add-on interest makes 3.49% look cheaper than it is |
| 0% promos at many merchants | Service charge of up to 10% on top |
| Credit line can be interest-free | Website and app list different rate ranges |
| One ID usually enough | No published late-fee rate for cash loans |
| Up to 24 months at partner stores | Limits can drop, per some user reviews |
Before you use BillEase: a checklist
- Download the app only from Google Play or the App Store, published by First Digital Finance Corporation.
- Decide which product you need: cash loan, merchant installment or Credit line.
- For store purchases, compare the installment price with the regular cash price.
- Read the disclosure statement and write down the total amount you will repay.
- Check the service charge and whether it is added to each installment.
- Make sure the first due date fits your payday.
- If you use the Credit line, plan to pay the full statement, not just the minimum due.
- Pay only through Pay Now in the app and save every receipt.
Quick answers
Is BillEase legit? Yes. First Digital Finance Corporation (SEC No. CS201516347) is on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026, with Billease as a registered platform.
What is BillEase's interest rate? The Google Play listing gives 0% to 3.49% a month, an APR of up to 41.88% and service charges of up to 10%. In BillEase's own ₱12,000 example, the true cost works out to about 6.6% a month.
How much can I borrow from BillEase? Between ₱500 and ₱50,000, according to the app listing. First limits are usually smaller and grow with on-time payments.
Can I get a BillEase cash loan without a payslip? Usually, yes. BillEase says a valid government ID is usually enough and that freelancers can apply, though it may ask for more documents and approval is not guaranteed.
Is the BillEase Credit line interest-free? Only if you pay the full statement balance by the due date, which can give you up to 62 days without interest. Paying only the minimum due means interest is charged.
What happens if I don't pay BillEase on time? Late penalties may apply and your credit score can be affected. Contact BillEase on or before the due date to ask for a payment arrangement.
Compare before you tap "Pay with BillEase"
BillEase is a solid, registered option, and its 0% promos and interest-free Credit line can save you money if you pay on time. For cash, though, it is one offer among many. Before you accept, compare offers from our partners on the total amount to repay, and see how it stacks up against other registered lenders such as JuanHand.
Sources: BillEase Google Play listing (checked 29 October 2026); billease.ph homepage, FAQ and scam awareness page (checked 29 October 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC rules on interest ceilings effective 1 April 2026; Philstar, 11 June 2026. Peso examples other than BillEase's own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website